Metals & Mining · NSE: HINDALCO · BSE: 500440
Hindalco: how the business works
Hindalco makes aluminium and copper in India and, through its subsidiary Novelis, rolled aluminium for drinks cans and cars abroad; FY26 revenue was ₹274,944 crore.
Follow Hindalco
Email me when Hindalco's page is updated after results.
We store your email address with Kit, our email provider, which also records when you sign up and whether you open or click our emails. We send a confirmation email first. See our privacy policy.
Hindalco Industries Limited · Mumbai, Maharashtra · Founded 1958
Updated for Q2 FY27 · checked
- Revenue, FY26
- ₹274,944 cr
- Profit to shareholders, FY26
- ₹13,391 cr
- Manufacturing units, FY26
- 48 in 10 countries
- Aluminium metal made in India, FY26
- 1,336 thousand tonnes
- Promoter (Aditya Birla group) holding, 30 Sep 2026
- 34.66%
The short version
Hindalco in 5 points
1 · What it sells
Hindalco makes aluminium and copper in India and, through its subsidiary Novelis, rolled aluminium sheet abroad, with FY26 revenue of ₹274,944 crore.
2 · Who pays it
In FY26 Novelis customers such as can makers and carmakers paid 58.1% of Hindalco's revenue, copper buyers 25.4%, aluminium metal buyers 10.9% and buyers of Indian rolled products and foil 5.7%.
3 · What it keeps from ₹100
Of every ₹100 that came in during FY26, Hindalco spent ₹63.7 on raw materials and kept ₹4.8 as profit, after ₹6,963 crore of net one-off costs, mostly the Oswego fires; operating EBITDA before one-offs was 12.7% of revenue (Cityfort calculation).
4 · Where the operating profit comes from
Indian aluminium making earned ₹18,884 crore of the company's ₹37,217 crore FY26 segment EBITDA (its own measure), against ₹14,546 crore for Novelis, ₹2,809 crore for copper and ₹978 crore for downstream.
5 · The one thing to watch
Borrowings rose from ₹61,931 crore on 31 Mar 2025 to ₹110,528 crore on 30 Sep 2026, while capital work in progress (plants being built) rose from ₹27,023 crore to ₹62,917 crore.
Sources: From Hindalco's FY26 annual report and its Q2 FY27 results · checked
01Where the money goes · FY26
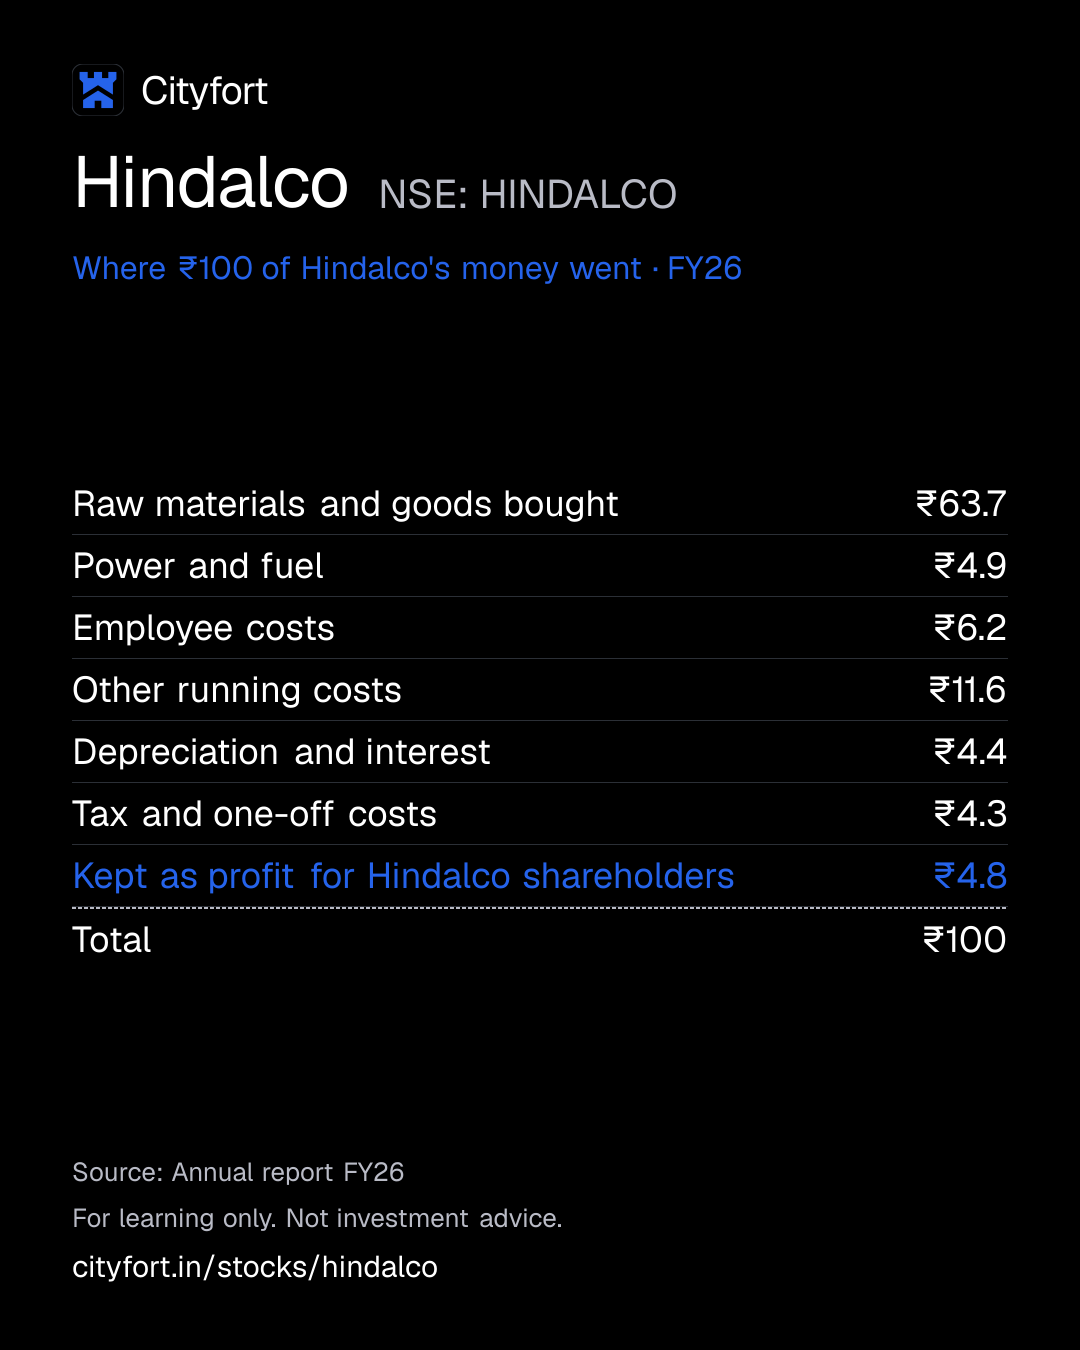
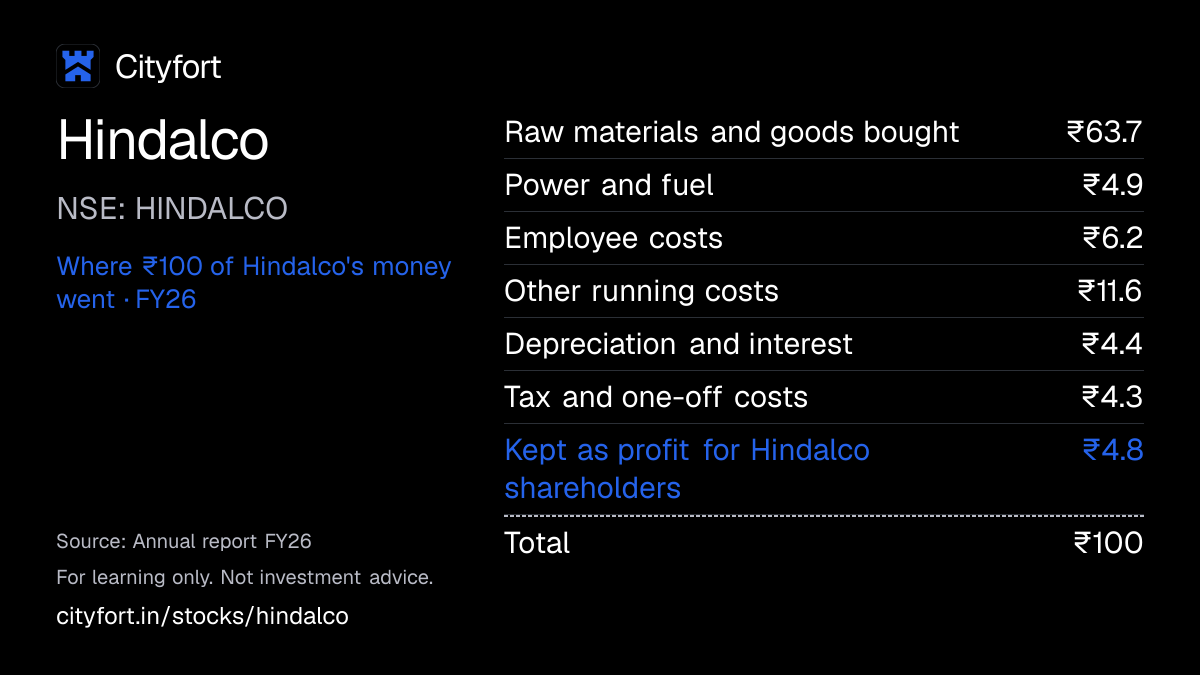
Where does ₹100 of Hindalco's money go?
Hindalco · FY26
Receipt for every ₹100
| Raw materials and goods bought | ₹63.7 |
|---|---|
| Power and fuel | ₹4.9 |
| Employee costs | ₹6.2 |
| Other running costs | ₹11.6 |
| Depreciation and interest | ₹4.4 |
| Tax and one-off costs | ₹4.3 |
| Kept as profit for Hindalco shareholders | ₹4.8 |
| Total | ₹100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly ₹100 because of rounding.
How this is worked out
Of every ₹100 that came in during FY26: revenue (₹274,944 crore) plus other income (₹2,889 crore). The tax line also holds ₹6,963 crore of net one-off costs, mostly the Oswego fires, and a ₹4 crore loss from joint ventures.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report results, explained in 5 points.
We'll email you once a week with what changed on Cityfort. Facts only, no tips. Unsubscribe any time.
We store your email address with Kit, our email provider, which also records when you sign up and whether you open or click our emails. We send a confirmation email first. See our privacy policy.
02The business in one line
What does Hindalco do?
Can makers, carmakers, builders and electrical firms pay Hindalco for aluminium and copper; metal and other raw materials take ₹63.7 of every ₹100, and ₹4.8 is left as profit.
- Indian aluminium making (the upstream segment) earned ₹18,884 crore of the company's ₹37,217 crore FY26 segment EBITDA (its own measure), more than Novelis's ₹14,546 crore, though Novelis brought in 58.1% of revenue.
- Borrowings rose from ₹61,931 crore on 31 Mar 2025 to ₹110,528 crore on 30 Sep 2026, while Hindalco builds new plants in the US and India.
03Who pays it
Who pays Hindalco?
Novelis customers: can makers, carmakers and others
58.1%
of revenue
Buyers of Novelis's rolled aluminium. Drinks cans were 62% of Novelis's FY26 shipments, cars 18%, specialities 17% and aerospace 3%.
Copper buyers
25.4%
of revenue
Buyers of copper cathode and continuous cast rods, including rods used for railway electrification in India.
Buyers of aluminium metal and alumina
10.9%
of revenue
Buyers of metal from Hindalco's Indian smelters; 79% of upstream sales were in India in Q2 FY27, against 75% a year earlier.
Buyers of Indian rolled products, extrusions and foil
5.7%
of revenue
Hindalco's FY26 sustainability report lists its Indian customers in building, cars and railways, electrical goods, packaging, food and pharma, among others.
- Novelis customers: can makers, carmakers and others58.1%
- Copper buyers25.4%
- Buyers of aluminium metal and alumina10.9%
- Buyers of Indian rolled products, extrusions and foil5.7%
Customer concentration
One customer of the Novelis segment paid ₹29,540 crore in FY26, about 10.7% of revenue (Cityfort calculation). Hindalco does not name it. A single customer passed 10% of revenue in FY22, FY23 and FY25 too, but not in FY24.
- Largest customer
- 11%
04How it makes money
How does Hindalco make money?
Indian smelting profit rises and falls with the world aluminium price; the other units earn on turning metal into products.
CARE names London Metal Exchange (LME) price swings as a key risk. Upstream segment EBITDA per ₹100 of segment revenue was ₹40.5 in FY22, ₹25.5 in FY23 and ₹45.6 in FY26. The company groups Novelis, downstream and copper as its non-LME-linked businesses; they earned ₹6,860 crore of EBITDA in Q2 FY27.
Aluminium upstream: segment EBITDA per ₹100 of segment revenue (Cityfort calculation from company figures)
₹25.5₹45.6
FY23 to FY26
- Hindalco mines bauxite in India and refines it into alumina.
- Its smelters turn alumina into aluminium; power and fuel cost ₹13,622 crore in FY26.
- It sells the metal at prices linked to the world aluminium price on the LME.
- When that price moves faster than costs, upstream profit moves with it.
- Novelis, the Indian rolling and foil units and copper turn metal into sheet, foil and rods.
↺ Step 5 feeds back into step 1.
05Business segments · FY26
Which businesses make up Hindalco?
Novelis
58.1%Rolled aluminium and recycling in North America, South America, Europe and Asia. FY26 segment EBITDA was ₹14,546 crore, on US accounting rules as the company reviews it.
Revenue ₹159,671 cr
Copper
25.4%Copper cathode, rods, precious metals and fertiliser. FY26 segment EBITDA was ₹2,809 crore.
Revenue ₹69,797 cr
Aluminium upstream
10.9%Bauxite, coal, alumina, smelting and power in India. FY26 segment EBITDA was ₹18,884 crore, the most of any segment, out of ₹37,217 crore in all.
Revenue ₹29,921 cr
Aluminium downstream
5.7%Rolled products, extrusions and foil in India. FY26 segment EBITDA was ₹978 crore.
Revenue ₹15,555 cr
How the mix changed
- Novelis
- Copper
- Aluminium upstream
- Aluminium downstream
Revenue by segment, FY22 to FY26.
₹ crore
See the numbers
06The numbers · Consolidated · ₹ crore
How has Hindalco done?
Revenue
₹274,944 crFY26
Revenue rose from ₹195,059 crore in FY22 to ₹274,944 crore in FY26, falling only in FY24 (3.2%); Q2 FY27's ₹91,708 crore was 38.8% above Q2 FY26.
₹ crore
See the numbers
Net profit
₹13,391 crFY26
Profit for shareholders fell to ₹13,391 crore in FY26 from ₹16,001 crore in FY25, after ₹6,963 crore of net one-off costs, mostly the Oswego fires, equal to 52% of FY26 profit.
₹ crore
See the numbers
Net profit for every ₹100 of revenue
₹4.9FY26
EBITDA here is a Cityfort calculation after one-off items, 10.2% of revenue in FY26 against 12.7% before them; the company's own FY26 figure, which leaves out one-offs and includes other income, was ₹38,097 crore.
Net margin: ₹ of net profit per ₹100 of revenue
See the numbers
Free cash flow
−₹19,846 crFY26
Free cash flow (operating cash flow minus spending on plants) was minus ₹19,846 crore in FY26, as capex rose to ₹30,096 crore and stock built up during the year took ₹24,518 crore of cash.
₹ crore · cash from operations minus spending on plants and equipment
See the numbers
See all yearly numbers
EBITDA = profit before interest, tax and wear-and-tear of assets. Financial year runs April to March (March year end). Net profit is the share belonging to the company's owners.
Sources (13)
- Integrated Annual Report FY23
- Integrated Annual Report FY24
- Integrated Annual Report FY25
- Integrated Annual Report FY26 (incl. BRSR)
- Consolidated financial results Q3 FY25 (XBRL filed with NSE)
- Consolidated financial results Q4 FY25 (XBRL filed with NSE)
- Consolidated financial results Q1 FY26 (XBRL filed with NSE)
- Consolidated financial results Q2 FY26 (XBRL filed with NSE)
- Consolidated financial results Q3 FY26 (XBRL filed with NSE)
- Consolidated financial results Q4 FY26 (XBRL filed with NSE)
- Consolidated financial results Q1 FY27 (XBRL filed with NSE)
- Consolidated financial results Q2 FY27 (XBRL filed with NSE)
- Unaudited financial results Q2 FY27 (quarter and half year to 30 Sep 2026)
07Who runs it
Who runs Hindalco, and did they deliver?
Kumar Mangalam Birla
Chairman (non-executive)
Chairman of the Aditya Birla Group, Hindalco's promoter.
Satish Pai
Managing Director
Bharat Goenka
Chief Financial Officer · since 2025
Appointed in Feb 2025.
Geetika Anand
Company Secretary
Steve Fisher
President and CEO, Novelis
Dev Ahuja
CFO, Novelis
What they said, and what happened
4 too early to tell · 1 delivered
Said on 7 Nov 2025
Management said in the Q2 FY26 earnings call (7 Nov 2025) that it would keep consolidated net debt below 2 times EBITDA while investing in a US$10 billion capex plan for FY26 to FY29.
Too early to tellWhat happened
The company put net debt at 1.80 times EBITDA on 30 Sep 2026, on its own basis. The plan runs to FY29.
Said on 12 Feb 2026
Managing Director Satish Pai said in his closing remarks on the Q3 FY26 call (12 Feb 2026) that the aim was to "get the hot mill in Bay Minette commissioned in the second half of this year".
Too early to tellWhat happened
The Q2 FY27 presentation (6 Nov 2026) says Bay Minette made its first cold-rolled coil in September and commercial shipments are to begin in Q1 FY28.
Said on 22 May 2026
Management said in the Q4 FY26 earnings call (22 May 2026) that the Oswego hot mill was on track to restart in the next few weeks.
DeliveredWhat happened
Hindalco told the exchanges on 10 Jun 2026 that the Oswego hot mill was back online; the Q2 FY27 presentation says production has normalised.
Said on 22 May 2026
Management said in the Q4 FY26 earnings call (22 May 2026) that FY27 capex would be about ₹12,000 crore in India and US$2.3–2.4 billion at Novelis.
Too early to tellWhat happened
Consolidated capex was ₹20,719 crore in H1 FY27, the company said in its Q2 FY27 presentation.
Said on 7 Aug 2026
Management said in the Q1 FY27 earnings call (7 Aug 2026) that it was speeding up Novelis's US$350–400 million structural cost reduction programmes.
Too early to tellWhat happened
The Q2 FY27 presentation reports over US$240 million of run-rate savings through Q2 FY27, with US$350–400 million targeted by the end of FY28.
Sources (7)
- Integrated Annual Report FY26 (incl. BRSR)
- Q1 FY27 earnings call transcript (call 7 Aug 2026)
- Q2 FY26 earnings call transcript (call 7 Nov 2025)
- Earnings presentation Q2 FY27
- Q3 FY26 earnings call transcript (call 12 Feb 2026)
- Q4 FY26 earnings call transcript (call 22 May 2026)
- Update: Novelis restarts Oswego hot mill
08What could go wrong
What could go wrong for Hindalco?
- Raw-material prices
Aluminium and copper prices
CARE lists swings in LME metal prices and raw-material costs as a constraint on Hindalco. Upstream segment EBITDA per ₹100 of segment revenue fell from ₹40.5 in FY22 to ₹25.5 in FY23, then reached ₹45.6 in FY26.
Watch Upstream EBITDA per tonne, which the company put at US$2,125 in Q2 FY27, against US$1,521 in Q2 FY26.
- Execution
Fires and floods at Novelis plants
Two fires at Novelis's Oswego (New York) hot mill, on 16 Sep 2025 and 20 Nov 2025, cost ₹7,357 crore net of insurance in FY26. A flood at Sierre (Switzerland) cost ₹879 crore net in FY25. In H1 FY27 Oswego still caused ₹5,134 crore of extra costs to serve customers, including tariffs, partly recovered.
Watch One-off (exceptional) items in each quarter's results; Q2 FY27 showed a net gain of ₹284 crore.
- Debt
Debt rising with big projects
Borrowings rose from ₹61,931 crore on 31 Mar 2025 to ₹110,528 crore on 30 Sep 2026. Management put Bay Minette's cost at about US$5 billion in Nov 2025, above the US$4.1 billion in CARE's Oct 2025 report. CARE named gearing above 1.50 times after an overrun as a downgrade trigger.
Watch Borrowings and the company's net debt to EBITDA (1.80 times on 30 Sep 2026, its basis) each quarter.
- Cash and liquidity
Cash tied up in stock
Operating cash flow fell to ₹10,250 crore in FY26 from ₹24,410 crore in FY25, as inventories took ₹24,518 crore of cash. In H1 FY27 operating cash flow was ₹2,825 crore against ₹19,344 crore of capex.
Watch Operating cash flow and inventories (₹86,413 crore on 30 Sep 2026) in the half-year and annual results.
- Concentration
One large customer
One unnamed customer of the Novelis segment paid ₹29,540 crore in FY26, about 10.7% of Hindalco's revenue. A single customer passed 10% in three of the four years before that too.
Watch The customer-concentration note in each annual report.
- Currency
Currency moves
Customers outside India paid 66.1% of FY26 revenue. In Q2 FY27 Novelis's EBITDA grew 32% in rupees but 20% in US dollars, the company said.
Watch The rupee–dollar rate and the gap between Novelis's rupee and dollar growth in the results presentation.
- Legal
CBI case over coal
The CBI filed a chargesheet based on allegations of misuse of coal from a mine deallocated in 2014-15, and a special court issued summons to Hindalco on 9 Apr 2025. The auditor says the possible financial impact cannot yet be determined.
Watch Whether the court frames charges, as reported in later annual reports or exchange filings.
Sources (9)
- CARE Ratings press release: Hindalco Industries Ltd (CARE AA+; Stable / CARE A1+ reaffirmed)
- Integrated Annual Report FY26 (incl. BRSR)
- Integrated Annual Report FY24
- Integrated Annual Report FY23
- Earnings presentation Q2 FY27
- Fire incident at Novelis Oswego plant
- Update: second fire at Novelis Oswego plant
- Consolidated financial results Q2 FY27 (XBRL filed with NSE)
- Q2 FY26 earnings call transcript (call 7 Nov 2025)
09Supporters and critics
What do supporters and critics point to?
What supporters point to
- CARE calls Hindalco one of the lowest-cost primary aluminium makers, and upstream FY26 segment EBITDA was ₹18,884 crore on ₹41,447 crore of segment revenue.
- Q2 FY27 revenue was ₹91,708 crore, 38.8% above Q2 FY26, and profit for shareholders was ₹7,532 crore, up 58.9%.
- The company's non-LME-linked EBITDA (Novelis, downstream and copper) rose from ₹3,930 crore in Q3 FY26 to ₹6,860 crore in Q2 FY27.
- CARE rates Hindalco AA+ (Stable), and the promoter group pledged no shares in the 12 quarters to Sep 2026.
What critics point to
- Borrowings rose from ₹61,931 crore on 31 Mar 2025 to ₹110,528 crore on 30 Sep 2026, and free cash flow was minus ₹19,846 crore in FY26.
- Net one-off costs of ₹6,963 crore, mostly the Oswego fires, equalled 52% of FY26 profit.
- Management's Bay Minette cost of about US$5 billion is above the US$4.1 billion in CARE's Oct 2025 report.
- Novelis's segment EBITDA per ₹100 of segment revenue fell from ₹11.9 in FY22 to ₹8.9 in FY26 (Cityfort calculation).
- The company said Q2 FY27 profit of its India business was helped by a move to a new tax regime, with its tax rate at 25% against 29%.
10What to watch next
What should you watch next at Hindalco?
Next event
Q3 FY27 results
Date not announced yet.
Bay Minette starts selling
The company said in its Q2 FY27 presentation (6 Nov 2026) that commercial shipments from the 600 thousand tonne plant are to begin in Q1 FY28.
Debt against the company's own limit
Management said in the Q2 FY26 call (7 Nov 2025) that it would keep net debt below 2 times EBITDA; the company's figure was 1.80 times on 30 Sep 2026. Borrowings were ₹110,528 crore.
Cash from operations
Operating cash flow was ₹2,825 crore in H1 FY27 against ₹19,344 crore of capex. The FY27 annual figures will show whether the stock build-up reverses.
11Key facts
Key facts about Hindalco
- What does Hindalco do?
- Hindalco Industries Limited, an Aditya Birla Group company based in Mumbai, makes aluminium and copper in India and owns Novelis, which rolls and recycles aluminium in North America, South America, Europe and Asia. Hindalco's FY26 revenue was ₹274,944 crore.
- How does Hindalco make money?
- Hindalco sells aluminium metal, rolled aluminium sheet, foil, extrusions and copper. In FY26 Hindalco's Indian aluminium upstream segment earned ₹18,884 crore and Novelis ₹14,546 crore of the company's ₹37,217 crore segment EBITDA, as the company measures it.
- Who are Hindalco's customers?
- Novelis customers paid 58.1% of Hindalco's FY26 revenue; drinks cans were 62% of Novelis's FY26 shipments and cars 18%. Copper buyers paid 25.4% of Hindalco's FY26 revenue, and one unnamed Novelis customer paid ₹29,540 crore, about 10.7%.
- How big is Hindalco?
- Hindalco's FY26 revenue was ₹274,944 crore and its profit for shareholders ₹13,391 crore, down from ₹16,001 crore in FY25. In Q2 FY27 (July–September 2026) Hindalco's revenue was ₹91,708 crore and profit ₹7,532 crore.
- Who owns Hindalco?
- On 30 Sep 2026 Hindalco's promoter group (Aditya Birla Group companies and family members) held 34.66% of the shares, with none pledged. Foreign institutions held 34.43%, including 4.25% behind global depositary receipts, and Indian institutions 20.97%.
- What is Novelis and how does it relate to Hindalco?
- Novelis Inc. is a wholly owned subsidiary of Hindalco that makes flat-rolled aluminium and recycles aluminium. Novelis shipped 3,557 thousand tonnes in FY26, and its FY26 revenue from outside customers was ₹159,671 crore, 58.1% of Hindalco's revenue.
- Where does Hindalco sell?
- Customers outside India paid ₹181,861 crore, or 66.1%, of Hindalco's FY26 revenue, and customers in India ₹93,083 crore, or 33.9%.
- How much does Hindalco borrow?
- Hindalco's borrowings, excluding leases, were ₹110,528 crore on 30 Sep 2026, up from ₹96,659 crore on 31 Mar 2026. After cash and short-term investments of ₹21,612 crore, Hindalco's net debt was ₹88,916 crore (Cityfort calculation from the Q2 FY27 results).
- Does Hindalco pay a dividend?
- Hindalco paid a dividend of ₹5.00 per share for FY26, the same as for FY25, which was 8.3% of FY26 basic earnings per share of ₹60.31.
Terms on this page
- Capital expenditure (capex)
- Credit rating
- Customer concentration
- Dividend payout ratio
- EBITDA
- FII and DII holding
- Free cash flow
- Market capitalisation
- Net debt
- Net profit
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does Hindalco sell?
Rolled aluminium from Novelis
Flat sheet made at Novelis plants abroad. Drinks cans were 62% of FY26 shipments, cars 18%, other speciality uses 17% and aircraft 3%. Outside customers paid ₹159,671 crore, 58.1% of FY26 revenue.
Aluminium metal and alumina (upstream)
Metal from Hindalco's Indian smelters, sold as ingots, billets and wire rods, plus alumina. Outside customers paid ₹29,921 crore, 10.9% of FY26 revenue; metal output was 1,336 thousand tonnes.
Rolled products, extrusions and foil in India (downstream)
Sheet, shaped aluminium sections and foil made in India. Outside customers paid ₹15,555 crore, 5.7% of FY26 revenue, on sales of 446 thousand tonnes.
Copper
Copper cathode (pure copper plates) and continuous cast rods, plus precious metals and DAP fertiliser from the same process. Outside customers paid ₹69,797 crore, 25.4% of FY26 revenue.
What it does
- Does: Runs 48 manufacturing units across 10 countries, counting Novelis
- Does: Mines its own bauxite in India and bought the company holding the Bandha coal block in Dec 2025
- Does: Recycles aluminium: 61% of what Novelis used in FY26 was recycled metal
- Does: Makes copper rods used for railway electrification in India
What it does not do
- Does not: Sell mostly in India: customers outside India paid 66.1% of FY26 revenue
- Does not: Earn profit in line with revenue: Novelis brought in 58.1% of FY26 revenue but 39% of segment EBITDA
- Does not: Name its largest customer: one Novelis customer paid ₹29,540 crore in FY26, but the company does not say who
Sources (1)
13How the money flows
13How the money flows · FY26
How does money flow through Hindalco?
Money in
- Revenue from operations₹274,944 cr
- Other income₹2,889 cr
The company
Hindalco
₹277,833 cr came in
Money out
- Raw materials and goods bought₹177,038 cr
- Power and fuel₹13,622 cr
- Employee costs₹17,148 cr
- Other running costs₹32,252 cr
- Depreciation and interest₹12,310 cr
- Tax and one-off costs (mostly the Oswego fires)₹12,072 cr
- Net profit for Hindalco shareholders₹13,391 cr
- In FY26 customers paid Hindalco ₹274,944 crore, and it earned ₹2,889 crore of other income.
- Raw materials and goods bought took ₹177,038 crore, net of a ₹14,082 crore rise in unsold stock. Power and fuel took ₹13,622 crore.
- Employees cost ₹17,148 crore, and other running costs, including write-downs of assets, ₹32,252 crore.
- Depreciation (wear and tear of plants) took ₹8,830 crore and interest ₹3,480 crore.
- Tax took ₹5,105 crore and net one-off costs ₹6,963 crore, mostly from fires at Novelis's Oswego plant. That left ₹13,391 crore of profit.
Sources (1)
14What it needs to run
14What it needs to run
What does Hindalco need to run?
Bauxite and alumina
CARE's Oct 2025 report says Hindalco gets all its bauxite and alumina from its own sources. It made 3,784 thousand tonnes of alumina in FY26.
Coal and power
The upstream segment includes Hindalco's coal and power operations. Power and fuel cost ₹13,622 crore in FY26. It bought the company holding the Bandha coal block in Dec 2025.
Used aluminium
Novelis melts down scrap: 61% of the metal it used in FY26 was recycled.
Plants
48 manufacturing units in 10 countries. Plants still being built (capital work in progress) were worth ₹62,917 crore on 30 Sep 2026.
People
The Indian company (excluding Novelis) had 11,395 permanent employees and 53,001 workers, including contract workers, on 31 Mar 2026.
15Where it sells
15Where it sells · FY26
Where does Hindalco sell?
- Outside India66.1%
- India33.9%
Sources (1)
16Where growth could come from
16Where growth could come from
Where could Hindalco's growth come from?
Management said in the Q4 FY26 earnings call (22 May 2026) that FY27 capex would be about ₹12,000 crore in India and US$2.3–2.4 billion at Novelis, mostly for Bay Minette. In the Q2 FY27 presentation (6 Nov 2026) the company said Bay Minette's commercial shipments are to begin in Q1 FY28.
Bay Minette plant in Alabama, US
Early600 thousand tonnes a year; first coil Sep 2026
Novelis's new rolling and recycling plant made its first cold-rolled coil in Sep 2026. Management put its cost at "around $5 billion" in the Q2 FY26 call; CARE's Oct 2025 report gave US$4.1 billion.
Status: Early, too early to judge.
Bigger Aditya smelter in Odisha
New+181 kt (FY28), +193 kt (FY29)
Hindalco told the exchanges on 7 Nov 2025 of a planned expansion adding 193 thousand tonnes a year to the 370 thousand tonne Aditya smelter, for ₹10,225 crore, by FY2029. The Q2 FY27 presentation lists a first phase of 181 thousand tonnes for FY28.
Status: New, recently announced.
More rolled products, foil and extrusions in India
WorkingEBITDA ₹545 cr (FY24) → ₹978 cr (FY26)
Downstream segment EBITDA rose from ₹545 crore in FY24 to ₹978 crore in FY26. Management said in the Q4 FY26 call that it aims to raise India downstream EBITDA fourfold by FY30.
Status: Working, on track against what the company said.
Indian projects pipeline
NewAbout ₹52,000 crore of projects
The Q2 FY27 presentation lists projects under way worth about ₹52,000 crore, including coal mines for FY27, an alumina refinery for FY28 and a 300 thousand tonne copper smelter for FY29. Hindalco told the exchanges on 7 Aug 2026 of a planned expansion adding 10 KTPA at the Kuppam unit for ₹768 crore plus ₹40 crore of interest during construction.
Status: New, recently announced.
Novelis cost savings
WorkingOver US$240 million a year so far
The company said in its Q2 FY27 presentation that Novelis had over US$240 million of yearly run-rate cost savings through Q2 FY27, against a US$350–400 million target by the end of FY28.
Status: Working, on track against what the company said.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
Sources (8)
- Q4 FY26 earnings call transcript (call 22 May 2026)
- Earnings presentation Q2 FY27
- Q2 FY26 earnings call transcript (call 7 Nov 2025)
- CARE Ratings press release: Hindalco Industries Ltd (CARE AA+; Stable / CARE A1+ reaffirmed)
- Capacity addition: Aditya Aluminium smelter +193 KT
- Integrated Annual Report FY25
- Integrated Annual Report FY26 (incl. BRSR)
- Capacity addition: Kuppam unit +10 KTPA
17Financial strength and debt
17Financial strength · 30 Sep 2026
How much debt does Hindalco have?
- Total debt₹110,528 cr
- Cash and investments₹21,612 cr
- Net debt (debt minus cash)₹88,916 cr
- Net worth (shareholders' money)₹159,666 cr
- Debt to equity
- 0.69×
- ₹ of debt for every ₹1 of shareholders' money
- Interest cover
- 6.3×
- how many times operating profit covers interest
- Borrowings here exclude lease liabilities (rent owed under long leases): ₹2,601 crore on 30 Sep 2026 and ₹2,502 crore on 31 Mar 2026. The 30 Sep 2026 figures are unaudited.
- Cash and short-term investments = cash ₹13,028 crore, other bank balances ₹1,571 crore and current investments ₹7,013 crore. Net debt is a Cityfort calculation from the Q2 FY27 results.
- The company's figure (definition not given) for net debt is ₹80,435 crore on 30 Sep 2026, which it puts at 1.80 times EBITDA on its own basis.
- Borrowings were ₹61,931 crore on 31 Mar 2025 and ₹96,659 crore on 31 Mar 2026. Capital work in progress (plants being built) rose from ₹27,023 crore to ₹62,917 crore between 31 Mar 2025 and 30 Sep 2026.
- Net debt on the same basis (Cityfort calculation from the annual reports) was ₹40,391 crore in FY22 and ₹73,967 crore in FY26.
- Operating EBITDA leaves out one-off items. Interest cover = FY26 profit before tax plus interest, divided by interest (Cityfort calculation). Net worth is the equity belonging to Hindalco's shareholders; debt to equity = borrowings ÷ net worth.
- CARE said in Oct 2025 that a major time or cost overrun on projects, taking overall gearing above 1.50 times, could lead to a downgrade.
Sources (6)
- Consolidated financial results Q2 FY27 (XBRL filed with NSE)
- Unaudited financial results Q2 FY27 (quarter and half year to 30 Sep 2026)
- Earnings presentation Q2 FY27
- Integrated Annual Report FY26 (incl. BRSR)
- Integrated Annual Report FY23
- CARE Ratings press release: Hindalco Industries Ltd (CARE AA+; Stable / CARE A1+ reaffirmed)
18Who owns it
18Who owns it · Q2 FY27
Who owns Hindalco?
- Promoters (founders or parent company)34.7%
- Foreign institutions (FII)34.4%
- Indian institutions (DII)21.0%
- Public and others9.9%
Promoter pledge
No promoter shares were pledged in Q2 FY27.
How ownership changed
* Pledged = share of the promoters' own holding reported as pledged. In older filings this can include shares “otherwise encumbered”; the governance flags say when.
† Others = Hindalco's employee benefit trust (shares for employee share plans).
Sources (12)
- Shareholding pattern, Sep 2026
- Shareholding pattern, Jun 2026
- Shareholding pattern, Mar 2026
- Shareholding pattern, Dec 2025
- Shareholding pattern, Sep 2025
- Shareholding pattern, Jun 2025
- Shareholding pattern, Mar 2025
- Shareholding pattern, Dec 2024
- Shareholding pattern, Sep 2024
- Shareholding pattern, Jun 2024
- Shareholding pattern, Mar 2024
- Shareholding pattern, Dec 2023
19What it does with profit
19What it does with profit
What does Hindalco do with its profit?
Dividend per share
₹5.00FY26
Dividend paid for each share, by financial year.
₹ per share
See the numbers
No buybacks or fund raises in the period covered.
20Governance signals
20Governance signals
What do Hindalco's governance filings show?
- Auditor
- Price Waterhouse & Co Chartered Accountants LLP
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- Hindalco's related-party dealings are set out in the related-party note of its FY26 annual report; this page does not summarise them. The promoter group held 34.66% of the shares on 30 Sep 2026.
- Credit rating
- CARE Ratings CARE AA+ (outlook Stable), 10 Oct 2025
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory · 30 Jun 2026
CBI chargesheet over coal from a deallocated mine
The FY26 annual report says the Central Bureau of Investigation (CBI) filed a chargesheet based on allegations of, among other things, misuse of coal mined in a mine deallocated in 2014-15. On 9 Apr 2025 the Special Judge (Prevention of Corruption Act) issued summons to the company. The company says that, subject to further arguments and the court's discretion, it appears at this stage that no charges are capable of being framed against the accused. The auditor drew attention to the matter in its FY26 report, saying the possible financial impact cannot yet be determined; its opinion was not modified.
regulatory · 7 Jan 2025
GST penalty order in Jabalpur
On 7 Jan 2025 Hindalco disclosed orders from the GST Commissioner's office in Jabalpur levying fines and penalty of ₹4.86 crore, imposed while denying refund benefits on export sales. The company said it prefers to appeal and does not expect a material impact.
other · 12 Feb 2026
Planned change of auditor
Price Waterhouse & Co's second term as auditor ends at the AGM in FY28. On 12 Feb 2026 Hindalco said it intends to appoint SRBC & Co LLP from then. This is the end of a term, not a resignation.
pledge · 19 Oct 2026
No promoter shares pledged
The promoter group had no shares pledged or otherwise encumbered in any of the 12 quarters from Dec 2023 to Sep 2026.
Sources (6)
- Integrated Annual Report FY26 (incl. BRSR)
- Shareholding pattern, Sep 2026
- CARE Ratings press release: Hindalco Industries Ltd (CARE AA+; Stable / CARE A1+ reaffirmed)
- GST orders-in-original, Jabalpur (penalty Rs 4.86 crore)
- Intention to appoint SRBC & Co LLP as statutory auditors from AGM in FY28
- Shareholding pattern, Dec 2023
21What the market paid
21What the market paid · price as of 11 Nov 2026
What did the market pay for Hindalco on 11 Nov 2026?
Price as of 11 Nov 2026 (shown for education; prices change daily).
Hindalco's NSE closing price was ₹962.30 as of 11 Nov 2026. Market value is that price × 224.72 crore shares (30 Sep 2026 shareholding pattern, including the employee trust's shares) = ₹216,251 crore. P/E (price ÷ earnings per share) was 11.1, on ₹86.44 of basic EPS for the four quarters to Q2 FY27. P/B (market value ÷ owners' equity of ₹159,666 crore on 30 Sep 2026) was 1.35. The FY26 dividend of ₹5.00 is 0.52% of the 11 Nov 2026 price. All ratios are Cityfort calculations.
- Share price
- ₹962.30
- Market value (market cap)
- ₹216,251 cr
- P/E
- 11.1×
- P/B
- 1.4×
Source: NSE CM bhavcopy 11 Nov 2026 (HINDALCO EQ close); Shareholding pattern, Sep 2026; Consolidated financial results Q2 FY27 (XBRL filed with NSE) and 4 more
Sources (7)
- NSE CM bhavcopy 11 Nov 2026 (HINDALCO EQ close)
- Shareholding pattern, Sep 2026
- Consolidated financial results Q2 FY27 (XBRL filed with NSE)
- Consolidated financial results Q1 FY27 (XBRL filed with NSE)
- Consolidated financial results Q4 FY26 (XBRL filed with NSE)
- Consolidated financial results Q3 FY26 (XBRL filed with NSE)
- Integrated Annual Report FY26 (incl. BRSR)
22How it got here
22How it got here
How did Hindalco get here?
1958
Milestone
Incorporated
Hindalco was incorporated in India in 1958, according to its FY26 annual report.
2007
Business-model change
Bought Novelis
Hindalco acquired Novelis, a maker of rolled aluminium, which took the group into plants across the globe.
2020
Business-model change
Novelis bought Aleris
Novelis acquired Aleris, another aluminium rolling company, according to CARE.
2024
Crisis
Flood at Sierre
A flood on 30 Jun 2024 hit Novelis's Sierre plant in Switzerland, costing ₹879 crore net of recoveries in FY25.
2025
Crisis
Two fires at Oswego
Fires on 16 Sep 2025 and 20 Nov 2025 stopped Novelis's Oswego hot mill in New York; FY26 costs net of insurance were ₹7,357 crore.
2025
Milestone
Coal block bought
Hindalco completed buying the company that holds the Bandha coal block on 1 Dec 2025.
2026
Milestone
Oswego restarts
Novelis announced on 10 Jun 2026 that the Oswego hot mill is back online.
2026
Milestone
First coil at Bay Minette
Novelis's 600 thousand tonne Bay Minette plant in Alabama made its first cold-rolled coil in Sep 2026.
2026
Milestone
AluChem deal ended
Hindalco and AluChem ended a US$125 million purchase agreement, signed in Jun 2025, on 1 Oct 2026, citing extended closing delays.
Sources (10)
- Integrated Annual Report FY26 (incl. BRSR)
- CARE Ratings press release: Hindalco Industries Ltd (CARE AA+; Stable / CARE A1+ reaffirmed)
- Fire incident at Novelis Oswego plant
- Update: second fire at Novelis Oswego plant
- Board approves acquisition of EMIL Mines and Mineral Resources (Bandha coal block)
- Completion of EMMRL (Bandha coal block) acquisition
- Update: Novelis restarts Oswego hot mill
- Earnings presentation Q2 FY27
- Acquisition of AluChem Companies, Inc. by Aditya Holdings LLC (US$125 mn)
- Sixth update: AluChem acquisition agreement terminated
23Sources and changes
Where every number on this page comes from
Sources (45 documents)
- S1Integrated Annual Report FY26 (incl. BRSR) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 30 Jun 2026
- S2Integrated Annual Report FY25 · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 28 Jul 2025
- S3Integrated Annual Report FY24 · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 29 Jul 2024
- S4Integrated Annual Report FY23 · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 28 Jul 2023
- S5Integrated Annual Report FY22 · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 30 Jul 2022
- S6Unaudited financial results Q2 FY27 (quarter and half year to 30 Sep 2026) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 6 Nov 2026
- S7Consolidated financial results Q2 FY27 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 6 Nov 2026
- S8Consolidated financial results Q1 FY27 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 7 Aug 2026
- S9Consolidated financial results Q4 FY26 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 22 May 2026
- S10Consolidated financial results Q3 FY26 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 12 Feb 2026
- S11Consolidated financial results Q2 FY26 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 7 Nov 2025
- S12Consolidated financial results Q1 FY26 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 12 Aug 2025
- S13Consolidated financial results Q4 FY25 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 20 May 2025
- S14Consolidated financial results Q3 FY25 (XBRL filed with NSE) · NSE (company XBRL filing) · Tier 1: company or exchange filing · 13 Feb 2025
- S15Audited financial results Q4 FY26 and FY26 (with dividend recommendation) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 22 May 2026
- S16Earnings presentation Q2 FY27 · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 6 Nov 2026
- S18Q1 FY27 earnings call transcript (call 7 Aug 2026) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 7 Aug 2026
- S19Q4 FY26 earnings call transcript (call 22 May 2026) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 26 May 2026
- S20Q3 FY26 earnings call transcript (call 12 Feb 2026) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 18 Feb 2026
- S21Q2 FY26 earnings call transcript (call 7 Nov 2025) · Hindalco Industries Ltd (company IR site; same document filed with NSE/BSE) · Tier 1: company or exchange filing · 13 Nov 2025
- S22CARE Ratings press release: Hindalco Industries Ltd (CARE AA+; Stable / CARE A1+ reaffirmed) · CARE Ratings Ltd · Tier 2: rating agency or regulator · 10 Oct 2025
- S23Shareholding pattern, Sep 2026 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 19 Oct 2026
- S24Shareholding pattern, Jun 2026 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 10 Jul 2026
- S25Shareholding pattern, Mar 2026 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 17 Apr 2026
- S26Shareholding pattern, Dec 2025 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 21 Jan 2026
- S27Shareholding pattern, Sep 2025 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 22 Oct 2025
- S28Shareholding pattern, Jun 2025 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 21 Jul 2025
- S29Shareholding pattern, Mar 2025 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 18 Apr 2025
- S30Shareholding pattern, Dec 2024 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 16 Jan 2025
- S31Shareholding pattern, Sep 2024 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 18 Oct 2024
- S32Shareholding pattern, Jun 2024 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 19 Jul 2024
- S33Shareholding pattern, Mar 2024 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 19 Apr 2024
- S34Shareholding pattern, Dec 2023 · NSE (company XBRL filing) · Tier 1: company or exchange filing · 18 Jan 2024
- S35NSE CM bhavcopy 11 Nov 2026 (HINDALCO EQ close) · NSE · Tier 1: company or exchange filing · 11 Nov 2026
- S36Acquisition of AluChem Companies, Inc. by Aditya Holdings LLC (US$125 mn) · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 24 Jun 2025
- S37Sixth update: AluChem acquisition agreement terminated · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 1 Oct 2026
- S38Fire incident at Novelis Oswego plant · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 18 Sep 2025
- S39Update: second fire at Novelis Oswego plant · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 21 Nov 2025
- S40Update: Novelis restarts Oswego hot mill · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 10 Jun 2026
- S41Capacity addition: Aditya Aluminium smelter +193 KT · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 7 Nov 2025
- S42Capacity addition: Kuppam unit +10 KTPA · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 7 Aug 2026
- S43Intention to appoint SRBC & Co LLP as statutory auditors from AGM in FY28 · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 12 Feb 2026
- S44Board approves acquisition of EMIL Mines and Mineral Resources (Bandha coal block) · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 20 May 2025
- S45Completion of EMMRL (Bandha coal block) acquisition · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 1 Dec 2025
- S46GST orders-in-original, Jabalpur (penalty Rs 4.86 crore) · Hindalco Industries Ltd (filed with NSE) · Tier 1: company or exchange filing · 7 Jan 2025
Changes to this page (v1 · 11 Nov 2026)
- v1 · 11 Nov 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a SEBI-registered adviser and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a SEBI-registered investment adviser.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Content is not an offer or solicitation to buy or sell any security.
Read the full disclaimerHide the full disclaimer
Cityfort publishes educational content that explains how listed companies work. Cityfort is not registered with the Securities and Exchange Board of India (SEBI) as an Investment Adviser or Research Analyst and does not provide investment advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security.
All information is taken from publicly available sources, mainly company filings on BSE and NSE, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management are reported as statements, with their date and source; they are not our forecasts.