Financial Services · NSE: AXISBANK · BSE: 532215
Axis Bank: how the business works
Axis Bank takes deposits and lends to households and businesses in India, earning ₹24,457 crore of bank-only profit in FY26.
Follow Axis Bank
Email me when Axis Bank's page is updated after results.
We store your email address with Kit, our email provider, which also records when you sign up and whether you open or click our emails. We send a confirmation email first. See our privacy policy.
Axis Bank Limited · Mumbai, Maharashtra · Founded 1993
Updated for Q2 FY27 · checked
- Deposits, 30 Sep 2026
- ₹1,452,066 cr
- Loans (net advances), 30 Sep 2026
- ₹1,373,727 cr
- Bank-only net profit, FY26
- ₹24,457 cr
- Customers, Sep 2026
- About 55 million
- Promoter (LIC) holding, Sep 2026
- 7.86%
The short version
Axis Bank in 5 points
1 · What it sells
Axis Bank lends to home buyers, consumers, small businesses and companies, with net loans of ₹1,373,727 crore at 30 Sep 2026, and earned ₹24,444 crore of fees in FY26 on cards, payments and wealth products.
2 · Who pays it
Borrowers pay Axis Bank interest, and at 30 Sep 2026 retail loans were 54% of its net loans, large and mid-sized companies 34% and small and medium businesses 12%.
3 · What it keeps from ₹100
Of every ₹100 that came in to Axis Bank alone in FY26 it kept ₹16 as profit, a year with a one-off ₹2,193 crore tax credit and one-off provisions of ₹1,231 crore and ₹2,001 crore; profit before provisions and tax was ₹42,817 crore.
4 · Where the operating profit comes from
Corporate and wholesale banking made ₹11,206 crore of Axis Bank's FY26 segment result before tax, retail banking ₹8,607 crore, treasury ₹5,037 crore and other banking ₹4,640 crore.
5 · The one thing to watch
Axis Bank's reported net interest margin fell from 4.07% in FY24 to 3.36% in Q2 FY27 (Jul–Sep 2026), and its CASA ratio from 47.2% at 31 Mar 2023 to 36% at 30 Sep 2026.
Sources: From Axis Bank's FY26 annual report and results filing, its Q2 FY27 press release and presentation, and its Q3 and Q4 FY26 call transcripts · checked
Sources (5)
- Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026)
- Earnings call transcript Q4 FY26 (call 25 Apr 2026)
- XBRL financial results Q4 FY26 and FY26 (audited), standalone
- Earnings call transcript Q3 FY26 (call 26 Jan 2026)
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
01Where the money goes · FY26
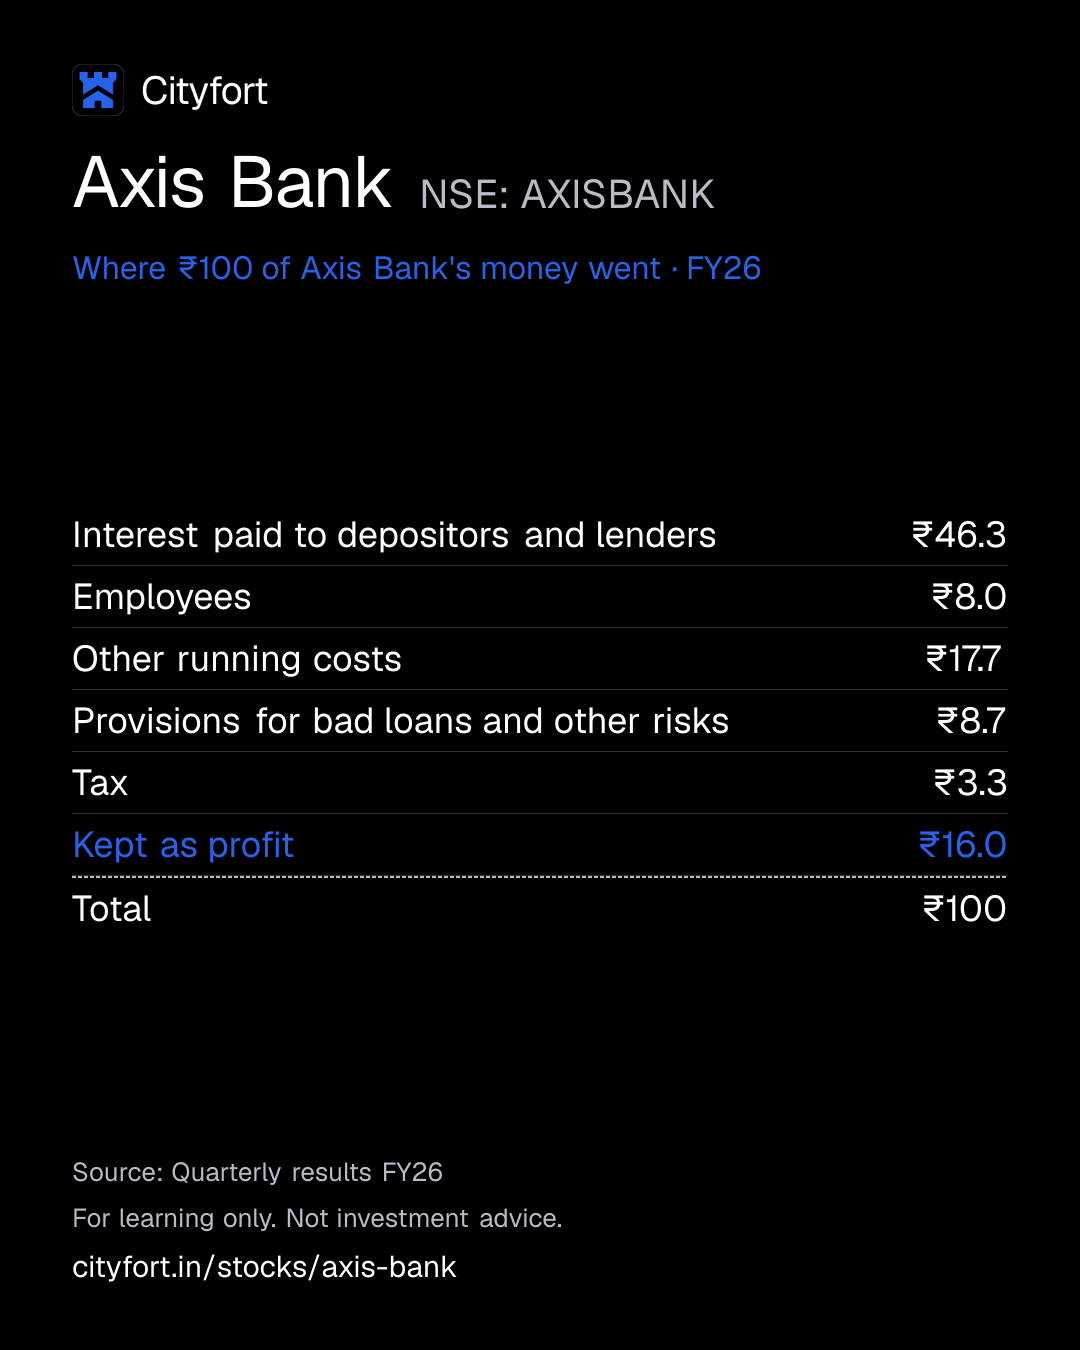
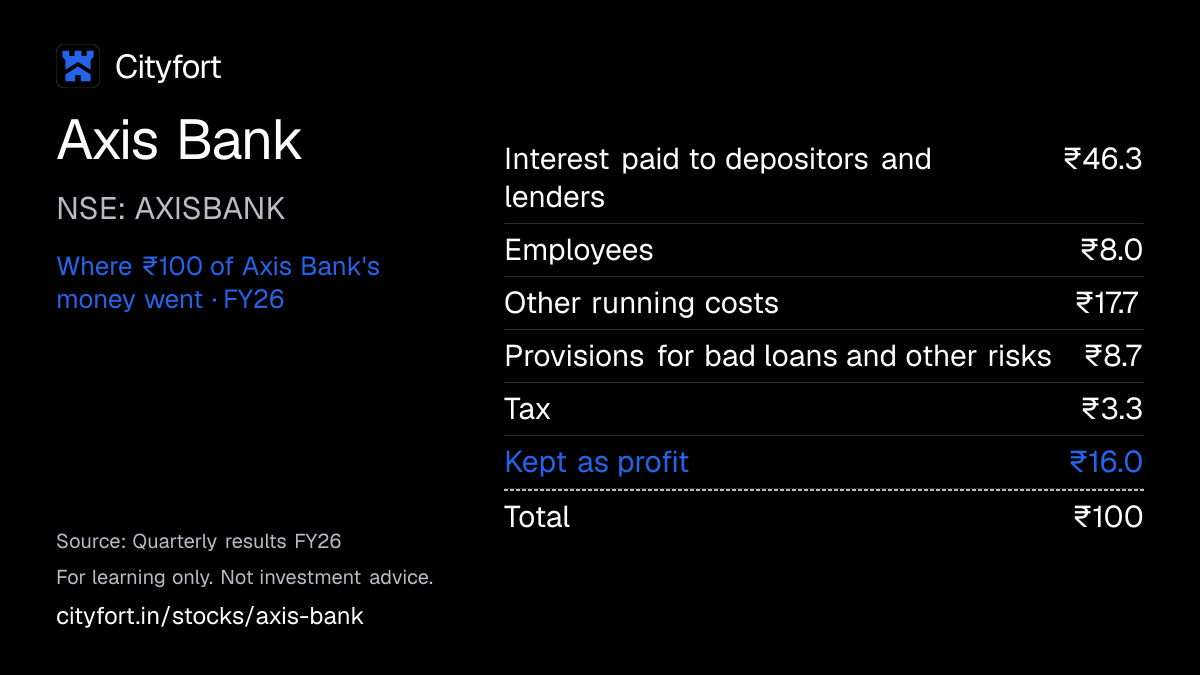
Where does ₹100 of Axis Bank's money go?
Axis Bank · FY26
Receipt for every ₹100
| Interest paid to depositors and lenders | ₹46.3 |
|---|---|
| Employees | ₹8.0 |
| Other running costs | ₹17.7 |
| Provisions for bad loans and other risks | ₹8.7 |
| Tax | ₹3.3 |
| Kept as profit | ₹16.0 |
| Total | ₹100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly ₹100 because of rounding.
How this is worked out
Of every ₹100 that came in to Axis Bank alone (standalone) in FY26. Money in = interest earned ₹127,032 crore + other income ₹26,131 crore. Cityfort calculation from the FY26 results filing.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report results, explained in 5 points.
We'll email you once a week with what changed on Cityfort. Facts only, no tips. Unsubscribe any time.
We store your email address with Kit, our email provider, which also records when you sign up and whether you open or click our emails. We send a confirmation email first. See our privacy policy.
02The business in one line
What does Axis Bank do?
Borrowers pay Axis Bank interest; in FY26, ₹46 of every ₹100 that came in went to depositors and lenders, and ₹16 was profit.
- Interest on loans and investments was ₹83 of every ₹100 that came in during FY26. Fees, treasury gains and other income made up the other ₹17.
- The promoter is Life Insurance Corporation of India (LIC), with 7.86% of shares at 30 Sep 2026. Mutual funds held 34.39%.
03Who pays it
Who pays Axis Bank?
Axis Bank does not disclose how much each type of customer pays.
Retail borrowers
Pay interest on home, personal, card, vehicle, rural and small-business loans: ₹739,905 crore, 54% of net loans at 30 Sep 2026. About 74% of retail loans were secured.
Large and mid-sized companies
Pay interest on corporate loans: ₹469,230 crore, 34% of net loans at 30 Sep 2026.
Small and medium businesses
Pay interest on SME loans: ₹164,592 crore, 12% of net loans at 30 Sep 2026.
Customers paying fees
Pay fees on cards, payments, accounts and wealth products: ₹24,444 crore in FY26. Retail customers paid 70% of fees in Q2 FY27.
How spread out the customers are
Axis Bank does not disclose income by customer. It had about 55 million customers at 30 Sep 2026. The shares above are the bank's own split of net loans, not of income.
04How it makes money
How does Axis Bank make money?
A bank earns the gap between the interest it charges and the interest it pays
Axis Bank takes in deposits, lends at higher rates and keeps the gap, called net interest income (NII). Current and savings (CASA) deposits pay little interest, so they keep that gap wide; their share of deposits fell from 47.2% (Mar 2023) to 36% (Sep 2026).
Interest kept per ₹100 of interest earned, after paying interest (bank only)
₹49.2₹44.1
FY22 to FY26
- Savers and firms deposit money, part of it in low-interest current and savings accounts
- The bank lends to households and businesses at higher rates
- The gap is net interest income: ₹56,048 crore in FY26
- Fees from cards, payments and wealth products add income
- Staff, branches and provisions for bad loans are paid out of it
- Profit adds to capital, which lets the bank lend more
↺ Step 6 feeds back into step 1.
05Business segments · FY26
Which businesses make up Axis Bank?
Retail banking
63.2%Loans, cards and deposits for individuals and small firms, incl. digital banking. Revenue counts internal transfers between segments; result is before tax.
Revenue ₹145,094 cr · Operating profit ₹8,607 cr
Corporate and wholesale banking
21.5%Loans and services for companies. Result is before tax, after provisions.
Revenue ₹49,329 cr · Operating profit ₹11,206 cr
Treasury
13.2%The bank's own investments and trading.
Revenue ₹30,410 cr · Operating profit ₹5,037 cr
Other banking
2.1%Other banking business the bank reports as a separate segment.
Revenue ₹4,908 cr · Operating profit ₹4,640 cr
How the mix changed
- Retail banking
- Corporate and wholesale banking
- Treasury
- Other banking
Revenue by segment, FY22 to FY26.
₹ crore
See the numbers
Sources (5)
- XBRL financial results Q4 FY22 and FY22 (audited), standalone
- XBRL financial results Q4 FY23 and FY23 (audited), standalone
- XBRL financial results Q4 FY24 and FY24 (audited), standalone
- XBRL financial results Q4 FY25 and FY25 (audited), standalone
- XBRL financial results Q4 FY26 and FY26 (audited), standalone
06The numbers · bank only (standalone) · ₹ crore
How has Axis Bank done?
Net interest income
₹56,048 crFY26
Bank-only net interest income (NII: interest earned minus interest paid) rose every year, from ₹33,132 crore in FY22 to ₹56,048 crore in FY26.
₹ crore · bank only (standalone) · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net profit
₹24,457 crFY26
Bank-only net profit was ₹24,457 crore in FY26, down from ₹26,373 crore in FY25; FY23 (₹9,580 crore) is after the ₹12,490 crore Citibank charge.
₹ crore · bank only (standalone)
See the yearly numbers
See the quarterly numbers
Net interest margin
3.69%FY26
Net interest margin, as reported, rose from 3.47% in FY22 to 4.07% in FY24, then fell to 3.69% in FY26 and 3.36% in Q2 FY27.
% · as reported by the company
See the numbers
Bad loans (gross NPA)
1.23%FY26
Gross NPA (loans not being repaid) fell from 2.82% in FY22 to 1.16% at 30 Sep 2026; a stricter counting rule raised FY26 quarters, such as 1.57% in Q1 FY26.
% of loans · gross and net (after provisions) non-performing assets
See the yearly numbers
See the quarterly numbers
See all yearly numbers
EPS is group (consolidated) basic EPS, as filed. FY23 is after the Citibank one-time charge.
Net interest income = interest earned on loans and investments minus interest paid on deposits and borrowings. Provisions = money set aside for loans that may not be repaid. Financial year runs April to March.
- Lending numbers and ratios here are Axis Bank alone (standalone), as the bank reports them. Total income, net profit and EPS under "The numbers" are group (consolidated) figures, which add subsidiaries such as Axis Finance and Axis AMC.
- FY23 includes a one-time charge of ₹12,490 crore for the Citibank India consumer business, including ₹8,714 crore of intangibles written off in full. Excluding it, the bank put FY23 profit at ₹21,933 crore, ROE at 18.38% and ROA at 1.82%; the table shows reported values.
- From Q1 FY26 the bank used stricter rules to count bad loans, mainly cash credit, overdraft and one-time settled accounts. This added ₹7,158 crore of gross NPAs and ₹2,809 crore of net NPAs in FY26. The bank says FY26 slippages, credit cost, NPA ratios, ROA and ROE are not comparable with FY25.
- FY26 one-offs: a ₹1,231 crore extra standard-asset provision in Q2, made "following an RBI advisory, post its FY25 annual inspection" on loans declassified from priority-sector lending; a voluntary ₹2,001 crore provision in Q4; and a ₹2,193 crore tax credit in Q4 on the Citibank intangibles. Management said the Q4 items, with a trading loss, were net neutral on profit.
- CASA ratio is a Cityfort calculation from the annual reports (CASA ÷ deposits at 31 Mar); the bank rounds FY26 to 40%. Cost-to-income is a Cityfort calculation (operating expenses ÷ (NII + other income)); the bank reports cost-to-assets instead (2.28% in FY26).
- Provision cover (PCR) excludes prudential write-offs, as the bank headlines it; including them it was 92.11% in FY26. NIM is as reported; Q2 FY27's 3.36% includes an 11 basis-point drag from FCNR(B) deposits, the bank says. Cityfort does not calculate NIM.
Sources (18)
- XBRL financial results Q4 FY22 and FY22 (audited), standalone
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
- Annual Report FY22 (2021-22) (zip on NSE)
- XBRL financial results Q4 FY23 and FY23 (audited), standalone
- Annual Report FY23 (2022-23) (zip on NSE)
- XBRL financial results Q4 FY24 and FY24 (audited), standalone
- Annual Report FY24 (2023-24)
- XBRL financial results Q4 FY25 and FY25 (audited), standalone
- XBRL financial results Q4 FY26 and FY26 (audited), standalone
- XBRL financial results Q3 FY25, standalone
- Press release and investor presentation Q3 FY26
- XBRL financial results Q1 FY26, standalone
- XBRL financial results Q2 FY26 (revised filing), standalone
- XBRL financial results Q3 FY26, standalone
- Investor presentation Q1 FY27 (revised filing)
- XBRL financial results Q1 FY27, standalone
- XBRL financial results Q2 FY27, standalone
- Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026)
07Who runs it
Who runs Axis Bank, and did they deliver?
Amitabh Chaudhry
Managing Director & CEO · since 2019
MD & CEO since 1 Jan 2019; his current term runs to 31 Dec 2027.
N. S. Vishwanathan
Part-time Chairman (independent)
The board re-appointed him on 25 Apr 2026 for 27 Oct 2026 to 26 Oct 2029, subject to RBI and shareholder approval.
Rajeev Mantri
Chief Financial Officer · since 2026
The board approved his appointment on 18 Jul 2026, effective 28 Sep 2026. His predecessor, Puneet Sharma, resigned on 28 Jun 2026 and left on 31 Aug 2026.
Munish Sharda
Executive Director
Re-appointed for three years from 27 Feb 2027; the bank filed RBI's approval on 4 Nov 2026.
What they said, and what happened
3 too early to tell
Said on 26 Jan 2026
Deliver a 3.8% net interest margin through the rate cycle (MD & CEO Amitabh Chaudhry).
Too early to tellWhat happened
Reported margin was 3.62% in Q4 FY26, 3.46% in Q1 FY27 and 3.36% in Q2 FY27. On 17 Oct 2026 management said it is working towards 3.8%, with no time frame.
Said on 18 Jul 2026
Grow 300 basis points faster than the industry (then-CFO Puneet Sharma).
Too early to tellWhat happened
Net loans grew 23% in the year to 30 Sep 2026, or 19% excluding FCNR(B)-backed loans. The documents read do not give industry growth for the same period.
Said on 25 Apr 2026
Keep the loan mix near 70% retail and SME and 30% wholesale, plus or minus 3–4 points (MD & CEO Amitabh Chaudhry).
Too early to tellWhat happened
At 30 Sep 2026 retail and SME loans were 65.8% of net loans (Cityfort calculation from the Q2 FY27 press release) and corporate loans 34%, as the bank states.
Sources (10)
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
- Board appoints Rajeev Mantri as Chief Financial Officer
- CFO Puneet Sharma resigns (relieved 31 Aug 2026); board approves re-appointment of Munish Sharda as ED
- RBI approval: re-appointment of Munish Sharda as Executive Director from 27 Feb 2027
- Earnings call transcript Q3 FY26 (call 26 Jan 2026)
- Investor presentation Q1 FY27 (revised filing)
- Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026)
- Earnings call transcript Q2 FY27 (call 17 Oct 2026)
- Earnings call transcript Q1 FY27 (call 18 Jul 2026)
- Earnings call transcript Q4 FY26 (call 25 Apr 2026)
08What could go wrong
What could go wrong for Axis Bank?
- Pricing
Narrower lending margin
Net interest margin, as reported, fell from 4.07% in FY24 to 3.69% in FY26 and 3.36% in Q2 FY27. The bank puts the FCNR(B) deposit drag in Q2 FY27 at 11 basis points.
Watch Quarterly NIM, with and without FCNR(B) deposits.
- Competition
Costlier deposits
CASA deposits fell from 47.2% of deposits (Mar 2023) to 36% (Sep 2026). ICRA says competition for retail deposits remains intense. Loans were 92.34% of deposits at 31 Mar 2026.
Watch CASA ratio and term-deposit growth each quarter.
- Debt
Bad loans and stricter counting
Gross slippages (loans newly turning bad) were ₹24,577 crore in FY26, against ₹19,474 crore in FY25. Stricter counting rules added ₹7,158 crore to gross NPAs in FY26, and ICRA calls asset quality monitorable.
Watch Gross slippages, gross NPA and credit cost each quarter.
- Other
One-off items in profit
FY26 profit includes a ₹2,193 crore tax credit and one-off provisions of ₹1,231 crore and ₹2,001 crore. FY23 profit is after a ₹12,490 crore Citibank charge.
Watch One-time items listed in each quarter's results and presentation.
- Regulation
Regulatory actions
The bank disclosed RBI penalties of ₹29.6 lakh and ₹37.3 lakh in 2025. A SEBI order of 28 Oct 2026 censured its subsidiary Axis Capital.
Watch RBI, SEBI and other regulator intimations filed with the exchanges.
- Governance
Changes in the top team
The CFO changed in 2026: Puneet Sharma left on 31 Aug 2026, and Rajeev Mantri took over on 28 Sep 2026 (board approval 18 Jul 2026). The Chairman's new term from 27 Oct 2026 needs RBI and shareholder approval. The CEO's term runs to 31 Dec 2027.
Watch RBI approvals and board filings on the Chairman and MD & CEO.
Sources (12)
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
- Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026)
- Earnings call transcript Q2 FY27 (call 17 Oct 2026)
- ICRA rationale: Axis Bank Limited, ratings reaffirmed and withdrawn for matured instruments (8 Apr 2026)
- Earnings call transcript Q4 FY26 (call 25 Apr 2026)
- Earnings call transcript Q3 FY26 (call 26 Jan 2026)
- XBRL financial results Q4 FY23 and FY23 (audited), standalone
- RBI monetary penalty of ₹29.6 lakh (order 29 Apr 2025)
- RBI (Foreign Exchange Dept) compounding penalty of ₹37.3 lakh
- SEBI final order (28 Oct 2026) issues regulatory censure against Axis Capital
- CFO Puneet Sharma resigns (relieved 31 Aug 2026); board approves re-appointment of Munish Sharda as ED
- Board appoints Rajeev Mantri as Chief Financial Officer
09Supporters and critics
What do supporters and critics point to?
What supporters point to
- Gross NPA fell from 2.82% of loans in FY22 to 1.16% at 30 Sep 2026; net NPA was 0.35%.
- CET1 capital (the core part of the bank's own money) was 14.61% of risk-weighted assets at 30 Sep 2026. The RBI CET1 minimum the bank cites is 8.00%.
- ICRA rated the bank's Tier II and infrastructure bonds AAA (Stable) on 8 Apr 2026. The rating covers debt, not the shares.
- The bank says it handled about 38% of UPI payments by volume as a payer bank in Q2 FY27 and had 13% of credit cards in force (Aug 2026).
- Domestic subsidiaries earned ₹2,051 crore in FY26, up 16%, and ₹1,210 crore in H1 FY27, up 29%.
What critics point to
- Net interest margin, as reported, fell from 4.07% in FY24 to 3.36% in Q2 FY27.
- CASA deposits fell from 47.2% of deposits in Mar 2023 to 36% in Sep 2026. ICRA says competition for retail deposits remains intense.
- Return on equity fell from 18.86% in FY24 to 13.15% in FY26; the bank says FY26 is not comparable after its stricter bad-loan rules.
- Gross slippages rose from ₹19,474 crore in FY25 to ₹24,577 crore in FY26. ICRA calls asset quality monitorable.
- RBI imposed a ₹29.6 lakh monetary penalty and a ₹37.3 lakh compounding penalty in 2025, and a SEBI order of 28 Oct 2026 censured its subsidiary Axis Capital.
10What to watch next
What should you watch next at Axis Bank?
Next event
Q3 FY27 results (date not announced yet)
Date not announced yet.
Net interest margin
It was 3.36% in Q2 FY27, the lowest of the 8 quarters shown. Management said on 17 Oct 2026 it is working towards 3.8%.
Deposit mix
CASA deposits were 36% of deposits at 30 Sep 2026. Deposits grew 21% in a year, or 17% excluding FCNR(B) deposits backed by international-branch loans.
Bad loans after the rule change
Gross NPA was 1.16% at 30 Sep 2026. Gross slippages were ₹4,762 crore in Q2 FY27, against ₹5,566 crore in Q1 FY27.
11Key facts
Key facts about Axis Bank
- What does Axis Bank do?
- Axis Bank is a private-sector bank in India. Axis Bank takes deposits and lends to individuals, small businesses and large companies. At 30 Sep 2026 Axis Bank held deposits of ₹1,452,066 crore and net loans of ₹1,373,727 crore.
- How does Axis Bank make money?
- Axis Bank earns mainly the gap between the interest it charges borrowers and the interest it pays depositors and lenders. In FY26, Axis Bank's own net interest income was ₹56,048 crore. Its other income, mainly fees, was ₹26,131 crore.
- Who are Axis Bank's customers?
- Axis Bank had about 55 million customers at 30 Sep 2026. Of Axis Bank's net loans then, retail borrowers had 54%, large and mid-sized companies 34%, and small and medium businesses 12%.
- How big is Axis Bank?
- Axis Bank's bank-only net profit was ₹24,457 crore in FY26, down from ₹26,373 crore in FY25. Group profit for Axis Bank shareholders, including subsidiaries, was ₹26,385 crore in FY26. Axis Bank had 6,414 branches at 30 Sep 2026.
- Who owns Axis Bank?
- Axis Bank's promoter is Life Insurance Corporation of India (LIC), with 7.86% of shares at 30 Sep 2026. Foreign investors held 41.16% of Axis Bank shares, Indian institutions 44.54% (mutual funds 34.39%), and individuals and others 6.43%.
- What is Axis Bank's net interest margin?
- Net interest margin is net interest income as a share of the money a bank has lent and invested. Axis Bank reported 3.69% for FY26, down from 4.07% in FY24. Axis Bank reported 3.36% for Q2 FY27 (Jul–Sep 2026).
- How many of Axis Bank's loans have gone bad?
- Axis Bank's gross NPA (loans not being repaid) was 1.16% of its loans at 30 Sep 2026. After money already set aside, Axis Bank's net NPA was 0.35%.
- What was Axis Bank's Citibank deal?
- Axis Bank completed its purchase of Citibank India's consumer business in 2023. Axis Bank booked a one-time charge of ₹12,490 crore for it in FY23, when its bank-only profit was ₹9,580 crore.
- Who runs Axis Bank?
- Amitabh Chaudhry has been Axis Bank's MD & CEO since 1 Jan 2019; his term runs to 31 Dec 2027. N. S. Vishwanathan is Axis Bank's part-time Chairman. The Axis Bank board approved Rajeev Mantri as CFO on 18 Jul 2026, effective 28 Sep 2026.
Sources (9)
- Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026)
- XBRL financial results Q4 FY26 and FY26 (audited), standalone
- XBRL financial results Q4 FY25 and FY25 (audited), standalone
- XBRL financial results Q4 FY26 and FY26 (audited), consolidated
- Shareholding pattern (XBRL), 30 Sep 2026
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
- XBRL financial results Q2 FY27, standalone
- XBRL financial results Q4 FY23 and FY23 (audited), standalone
- Board appoints Rajeev Mantri as Chief Financial Officer
Terms on this page
- CASA ratio
- Credit rating
- FII and DII holding
- Gross and net NPA
- Market capitalisation
- Net interest margin (NIM)
- Net profit
- Promoter holding
- Provision coverage ratio (PCR)
- Public shareholding
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does Axis Bank sell?
Deposits: savings, current and fixed
Accounts for people and firms: ₹1,452,066 crore at 30 Sep 2026. Of this, 36% sat in current and savings accounts (CASA), which pay little or no interest.
Retail loans and cards
₹739,905 crore at 30 Sep 2026, 54% of loans. At 31 Mar 2026 home loans were 26% of retail loans, and personal loans and credit cards 19%.
Loans to large and mid-sized companies
₹469,230 crore at 30 Sep 2026, 34% of loans. The bank says about 91% of this book was rated A- or above.
Loans to small and medium businesses (SME)
₹164,592 crore at 30 Sep 2026, 12% of loans.
Fees and services
Fees on cards, payments, accounts and wealth products brought in ₹24,444 crore in FY26. Retail customers paid 70% of fees in Q2 FY27.
Wealth, funds and broking
Burgundy, the wealth arm, managed ₹819,868 crore at 30 Sep 2026. Subsidiaries run a mutual fund (Axis AMC), broking, investment banking and a non-bank lender (Axis Finance).
What it does
- Does: Takes deposits from people and businesses
- Does: Lends to home buyers, consumers, small businesses and large companies
- Does: Issues credit cards: about 13% of cards in force in India (Aug 2026, bank's figure)
- Does: Owns Axis Finance, Axis Securities and Axis Capital fully, and 75% of Axis AMC
What it does not do
- Does not: Belong to a business family: its promoter is LIC, with 7.86% of shares (Sep 2026)
- Does not: Own Axis Max Life Insurance outright: Axis entities held 19.02% at 31 Mar 2026
- Does not: Run a separate Citibank in India: it bought Citibank India's consumer business in 2023
13How the money flows
13How the money flows · FY26
How does money flow through Axis Bank?
Money in
- Interest earned (loans, investments and other)₹127,032 cr
- Fees, treasury gains and other income₹26,131 cr
The company
Axis Bank
₹153,163 cr came in
Money out
- Interest paid to depositors and lenders₹70,984 cr
- Employees₹12,266 cr
- Other running costs₹27,096 cr
- Provisions for bad loans and other risks₹13,263 cr
- Tax₹5,097 cr
- Net profit (bank only)₹24,457 cr
- These are Axis Bank's own FY26 accounts (standalone), without its subsidiaries.
- Savers, companies and other lenders provide the money. In FY26 the bank paid them ₹70,984 crore of interest.
- It lends and invests that money. Interest earned was ₹127,032 crore, and fees and other income added ₹26,131 crore.
- Staff cost ₹12,266 crore and other running costs ₹27,096 crore.
- After ₹13,263 crore of provisions for possible bad loans and ₹5,097 crore of tax, ₹24,457 crore was profit.
14What it needs to run
14What it needs to run
What does Axis Bank need to run?
A banking licence and capital
RBI requires each bank to hold a minimum of its own money (capital) against its loans and other assets, weighted by risk. That share is called CRAR. Axis Bank's was 16.42% at 31 Mar 2026; the RBI minimum the bank cites is 11.50%.
Deposits
Deposits of ₹1,452,066 crore at 30 Sep 2026 fund most of its lending. Fixed (term) deposits were ₹922,527 crore of that.
Borrowings
Bank-only borrowings were ₹235,271 crore at 31 Mar 2026, up from ₹184,147 crore a year earlier.
Branches and ATMs
6,414 branches and extension counters and 12,533 ATMs and cash recyclers at 30 Sep 2026, up from 5,976 branches a year earlier.
People
101,337 permanent employees at 31 Mar 2026, plus 10,234 others, the BRSR report says.
15Where growth could come from
15Where growth could come from
Where could Axis Bank's growth come from?
MD & CEO Amitabh Chaudhry said on 25 Apr 2026 that the bank still expects a 3.8% net interest margin through the cycle. On the 17 Oct 2026 call, management said it is working towards that level but gave no time frame. Then-CFO Puneet Sharma said on 18 Jul 2026 that the bank's one growth guidance is 300 basis points above the industry.
Net interest margin back to 3.8%
Behind3.36% in Q2 FY27 (3.47% excluding FCNR(B) deposits, bank's figure)
The CEO restated the 3.8% through-cycle aim on 25 Apr 2026. Reported margin since: 3.62% (Q4 FY26), 3.46% (Q1 FY27), 3.36% (Q2 FY27).
Status: Behind, behind the company's own plan.
Loan growth against the industry
EarlyNet loans +23% in the year to 30 Sep 2026 (+19% excluding FCNR(B)-backed loans)
Then-CFO Puneet Sharma said on 18 Jul 2026 the aim is growth 300 basis points above the industry. The documents read do not give industry growth for the same period.
Status: Early, too early to judge.
Foreign-currency deposits from non-resident Indians
NewAbout ₹101,800 crore (₹1,018 billion, bank's figure) of FCNR(B) deposits raised in Q2 FY27, about 8% of the market
FCNR(B) deposits are held in foreign currency by non-resident Indians. Deposits grew 21% in the year to 30 Sep 2026, or 17% excluding FCNR(B) deposits backed by loans of the international branches, the bank says.
Status: New, recently announced.
Loan mix near 70% retail and SME, 30% companies
MixedRetail and SME 65.8%, companies 34% of net loans (Sep 2026)
The CEO said on 25 Apr 2026 the bank aims for about 70:30, "plus-minus 3% or 4%". The bank states the 54% retail, 12% SME and 34% corporate shares; the 65.8% retail-and-SME total is a Cityfort calculation from the Q2 FY27 press release.
Status: Mixed, partly on track.
Wealth management and subsidiaries
WorkingBurgundy assets ₹819,868 crore (+27%); subsidiaries' profit ₹1,210 crore in H1 FY27 (+29%)
Burgundy is the bank's wealth arm. Domestic subsidiaries earned ₹2,051 crore in FY26, up 16%.
Status: Working, on track against what the company said.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
Sources (6)
- Earnings call transcript Q4 FY26 (call 25 Apr 2026)
- Earnings call transcript Q2 FY27 (call 17 Oct 2026)
- Earnings call transcript Q1 FY27 (call 18 Jul 2026)
- Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026)
- Investor presentation Q1 FY27 (revised filing)
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
16Financial strength: capital, bad loans, deposits
16Financial strength · FY26
How strong is Axis Bank's balance sheet?
- Loans given (advances)₹12.34 lakh cr
- Deposits taken₹13.36 lakh cr
Loans were 92% of deposits (credit–deposit ratio) at the end of FY26.
- Capital adequacy (CRAR)
- 16.42%
- capital as a share of risk-weighted loans; regulators set a minimum
- Core equity (CET1)
- 14.38%
- the highest-quality part of that capital
- Gross NPA
- 1.23%
- loans not being repaid, as % of all loans
- Net NPA
- 0.37%
- the same, after money already set aside
- Provision cover
- 70.0%
- share of bad loans already provided for
- CASA ratio
- 39.6%
- deposits in current and savings accounts, which usually pay low interest
- Cost to income
- 47.9%
- ₹ of running costs per ₹100 of income after interest paid
- Return on assets
- 1.45%
- profit as % of everything the lender owns
- Return on equity
- 13.15%
- profit as % of shareholders' money
Figures as on FY26 year end (standalone, as banks report these ratios). Reported by the company; see the dates on each source.
17Who owns it
17Who owns it · Q2 FY27
Who owns Axis Bank?
- Promoters (founders or parent company)7.9%
- Foreign institutions (FII)41.2%
- Indian institutions (DII)44.5%
- Public and others6.4%
Promoter pledge
No promoter shares were pledged in Q2 FY27.
How ownership changed
* Pledged = share of the promoters' own holding reported as pledged. In older filings this can include shares “otherwise encumbered”; the governance flags say when.
Sources (12)
- Shareholding pattern (XBRL), 31 Dec 2023
- Shareholding pattern (XBRL), 31 Mar 2024
- Shareholding pattern (XBRL), 30 Jun 2024
- Shareholding pattern (XBRL), 30 Sep 2024
- Shareholding pattern (XBRL), 31 Dec 2024
- Shareholding pattern (XBRL), 31 Mar 2025
- Shareholding pattern (XBRL), 30 Jun 2025
- Shareholding pattern (XBRL), 30 Sep 2025
- Shareholding pattern (XBRL), 31 Dec 2025
- Shareholding pattern (XBRL), 31 Mar 2026
- Shareholding pattern (XBRL), 30 Jun 2026
- Shareholding pattern (XBRL), 30 Sep 2026
18What it does with profit
18What it does with profit
What does Axis Bank do with its profit?
Dividend per share
₹1.00FY26
Dividend paid for each share, by financial year.
₹ per share
See the numbers
No buybacks or fund raises in the period covered.
19Governance signals
19Governance signals
What do Axis Bank's governance filings show?
- Auditor
- M M Nissim & Co. LLP and KKC & Associates LLP (joint statutory auditors, FY26)
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- Axis Bank's main related parties are its subsidiaries and its associate, Axis Max Life Insurance. At 31 Mar 2026 it owned 100% of Axis Finance, Axis Securities and Axis Capital, and 75% of Axis AMC. Axis entities held 19.02% of Axis Max Life; a 1 Jun 2026 filing allows up to ₹380.6 crore more, to 19.99%. A board committee approved putting ₹1,500 crore into Axis Finance by 31 Mar 2027.
- Credit rating
- ICRA AAA (Tier II and infrastructure bonds) (outlook Stable), 8 Apr 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory · 4 Feb 2026
Penalties and demands, 2025–2026
The bank disclosed an RBI monetary penalty of ₹29.6 lakh (order of 29 Apr 2025) and an RBI foreign-exchange compounding of ₹37.3 lakh (12 Feb 2025). An appeals tribunal under the money-laundering law (PMLA) cut a fine from ₹2.643 crore to ₹39.2 lakh (27 Mar 2025). The Employees' Provident Fund Organisation (EPFO) raised a ₹1.14 crore demand for interest and damages on delayed remittances (Feb 2026). Amounts are as filed.
regulatory · 30 Oct 2026
SEBI orders on the Max Life deal and Axis Capital
SEBI's final order of 24 Aug 2026 disposed of proceedings against Axis Bank, Axis Securities and Axis Capital over the purchase of Max Life shares "without issuance of any direction or imposition of any penalty", the bank said. A SEBI final order of 28 Oct 2026 issued a regulatory censure against Axis Capital, a subsidiary.
other · 30 Sep 2026
LIC is the promoter; GDR depository shown from Jun 2026
The promoter group is LIC and 13 LIC and IDBI group entities; only LIC holds shares (7.86%, Sep 2026), none pledged. From Jun 2026 the filings show The Bank of New York Mellon, depository for the London-listed GDRs, with 3.11% inside foreign investors; the filing gives no reason. RBI approved on 30 Jan 2026 an amended deposit agreement giving GDR holders voting rights, subject to conditions.
Sources (13)
- Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements
- Additional investment of up to ₹380.6 crore in Axis Max Life Insurance; Axis entities stake 19.02% to 19.99%
- Board committee approves ₹1,500 crore infusion in Axis Finance by 31 Mar 2027
- ICRA rationale: Axis Bank Limited, ratings reaffirmed and withdrawn for matured instruments (8 Apr 2026)
- RBI monetary penalty of ₹29.6 lakh (order 29 Apr 2025)
- RBI (Foreign Exchange Dept) compounding penalty of ₹37.3 lakh
- PMLA Appellate Tribunal fine reduced to ₹39.2 lakh (order 27 Mar 2025)
- EPFO demand of ₹1.14 crore (interest and damages, delayed pension-scheme remittance)
- SEBI final order (24 Aug 2026) disposes of Max Life share-purchase proceedings against Axis Bank, ASL, ACL without direction or penalty
- SEBI final order (28 Oct 2026) issues regulatory censure against Axis Capital
- Shareholding pattern (XBRL), 30 Sep 2026
- Shareholding pattern (XBRL), 30 Jun 2026
- RBI approves amended GDR deposit agreement (voting rights for GDR holders, subject to conditions)
20What the market paid
20What the market paid · price as of 11 Nov 2026
What did the market pay for Axis Bank on 11 Nov 2026?
Price as of 11 Nov 2026 (shown for education; prices change daily).
Price as of 11 Nov 2026: ₹1,336.40, the NSE closing price. Market value: ₹416,113 crore, a Cityfort calculation from that price and the 3,113,689,740 shares in the 30 Sep 2026 shareholding pattern. P/E is the share price divided by one year's profit per share: here FY26 group EPS of ₹85.04, giving 15.7. P/B divides the price by book value (shareholders' money) per share: bank-only ₹703 at 30 Sep 2026, giving 1.90. EV/EBITDA is not shown, because interest is a bank's main running cost.
- Share price
- ₹1,336.40
- Market value (market cap)
- ₹416,113 cr
- P/E
- 15.7×
- P/B
- 1.9×
Source: NSE capital-market bhavcopy, 11 Nov 2026; Shareholding pattern (XBRL), 30 Sep 2026; XBRL financial results Q4 FY26 and FY26 (audited), consolidated and 1 more
21How it got here
21How it got here
How did Axis Bank get here?
1993
Milestone
Incorporated as UTI Bank
The bank was incorporated in 1993 as UTI Bank and later renamed Axis Bank.
1999
Milestone
Shares listed
Its first public share sale, in 1999, drew over 1 lakh retail investors, the bank says.
2005
Milestone
GDRs listed in London
Global depositary receipts (GDRs) listed on the London Stock Exchange, raising US$257.03 million.
2011
Milestone
Investment banking added
Bought Enam Securities' investment banking and equity capital markets business.
2019
Milestone
New MD & CEO
Amitabh Chaudhry became MD & CEO on 1 Jan 2019.
2020
Milestone
₹12,500 crore share sale
Raised ₹12,500 crore by selling new shares to large investors (a qualified institutional placement).
2021
Milestone
Max Life Insurance partnership
Began a strategic partnership with Max Life Insurance; Axis entities held 19.02% at 31 Mar 2026.
2023
Business-model change
Citibank India consumer business bought
Completed the purchase of Citibank India's consumer business. FY23 carried a ₹12,490 crore one-time charge for it.
2025
Milestone
Citibank customers moved over
Moved more than 2 million Citibank India customers onto Axis Bank's systems.
2025
Crisis
Stricter bad-loan counting
From Apr–Jun 2025 tighter rules added ₹7,158 crore of gross NPAs over FY26; gross NPA rose to 1.57% in Q1 FY26.
22Sources and changes
Where every number on this page comes from
Sources (61 documents)
- S1Integrated Annual Report FY26 (2025-26), incl. standalone and consolidated financial statements · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 25 Jun 2026
- S3Annual Report FY24 (2023-24) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 2 Jul 2024
- S4Annual Report FY23 (2022-23) (zip on NSE) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 26 Jun 2023
- S5Annual Report FY22 (2021-22) (zip on NSE) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 8 Sep 2022
- S6Press release and investor presentation Q2 FY27 (quarter ended 30 Sep 2026) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 17 Oct 2026
- S7Investor presentation Q1 FY27 (revised filing) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 18 Jul 2026
- S8Press release and investor presentation Q3 FY26 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 26 Jan 2026
- S9Earnings call transcript Q2 FY27 (call 17 Oct 2026) · Axis Bank investor relations (axis.bank.in) · Tier 1: company or exchange filing · 26 Oct 2026
- S10Earnings call transcript Q1 FY27 (call 18 Jul 2026) · Axis Bank investor relations (axis.bank.in) · Tier 1: company or exchange filing · 24 Jul 2026
- S11Earnings call transcript Q4 FY26 (call 25 Apr 2026) · Axis Bank investor relations (axis.bank.in) · Tier 1: company or exchange filing · 30 Apr 2026
- S12Earnings call transcript Q3 FY26 (call 26 Jan 2026) · Axis Bank investor relations (axis.bank.in) · Tier 1: company or exchange filing · 2 Feb 2026
- S13ICRA rationale: Axis Bank Limited, ratings reaffirmed and withdrawn for matured instruments (8 Apr 2026) · ICRA Limited (icra.in) · Tier 2: rating agency or regulator · 8 Apr 2026
- S14Business Responsibility and Sustainability Report FY26 (filed with the exchange) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 25 Jun 2026
- S15XBRL financial results Q2 FY27, standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 17 Oct 2026
- S16XBRL financial results Q2 FY27, consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 17 Oct 2026
- S17XBRL financial results Q1 FY27, standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 18 Jul 2026
- S18XBRL financial results Q1 FY27, consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 18 Jul 2026
- S19XBRL financial results Q4 FY26 and FY26 (audited), standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 28 Apr 2026
- S20XBRL financial results Q4 FY26 and FY26 (audited), consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 28 Apr 2026
- S21XBRL financial results Q3 FY26, standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 26 Jan 2026
- S22XBRL financial results Q3 FY26, consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 26 Jan 2026
- S23XBRL financial results Q2 FY26 (revised filing), standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 4 Dec 2025
- S24XBRL financial results Q2 FY26 (revised filing), consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 4 Dec 2025
- S25XBRL financial results Q1 FY26, standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 17 Jul 2025
- S26XBRL financial results Q1 FY26, consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 17 Jul 2025
- S27XBRL financial results Q4 FY25 and FY25 (audited), standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 24 Apr 2025
- S28XBRL financial results Q4 FY25 and FY25 (audited), consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 24 Apr 2025
- S29XBRL financial results Q3 FY25, standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 16 Jan 2025
- S30XBRL financial results Q3 FY25, consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 16 Jan 2025
- S31XBRL financial results Q4 FY24 and FY24 (audited), standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 25 Apr 2024
- S32XBRL financial results Q4 FY24 and FY24 (audited), consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 25 Apr 2024
- S33XBRL financial results Q4 FY23 and FY23 (audited), standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 28 Apr 2023
- S34XBRL financial results Q4 FY23 and FY23 (audited), consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 28 Apr 2023
- S35XBRL financial results Q4 FY22 and FY22 (audited), standalone · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 29 Apr 2022
- S36XBRL financial results Q4 FY22 and FY22 (audited), consolidated · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 29 Apr 2022
- S38Shareholding pattern (XBRL), 30 Sep 2026 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 9 Oct 2026
- S39Shareholding pattern (XBRL), 30 Jun 2026 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 13 Jul 2026
- S40Shareholding pattern (XBRL), 31 Mar 2026 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 13 Apr 2026
- S41Shareholding pattern (XBRL), 31 Dec 2025 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 9 Jan 2026
- S42Shareholding pattern (XBRL), 30 Sep 2025 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 10 Oct 2025
- S43Shareholding pattern (XBRL), 30 Jun 2025 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 18 Jul 2025
- S44Shareholding pattern (XBRL), 31 Mar 2025 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 9 Apr 2025
- S45Shareholding pattern (XBRL), 31 Dec 2024 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 11 Jan 2025
- S46Shareholding pattern (XBRL), 30 Sep 2024 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 10 Oct 2024
- S47Shareholding pattern (XBRL), 30 Jun 2024 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 12 Jul 2024
- S48Shareholding pattern (XBRL), 31 Mar 2024 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 10 Apr 2024
- S49Shareholding pattern (XBRL), 31 Dec 2023 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 19 Jan 2024
- S50NSE capital-market bhavcopy, 11 Nov 2026 · NSE (nsearchives.nseindia.com) · Tier 1: company or exchange filing · 11 Nov 2026
- S51Outcome of board meeting: final dividend ₹1 per share for FY26 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 25 Apr 2026
- S52Board committee approves ₹1,500 crore infusion in Axis Finance by 31 Mar 2027 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 18 Mar 2026
- S53Additional investment of up to ₹380.6 crore in Axis Max Life Insurance; Axis entities stake 19.02% to 19.99% · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 1 Jun 2026
- S54SEBI final order (24 Aug 2026) disposes of Max Life share-purchase proceedings against Axis Bank, ASL, ACL without direction or penalty · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 25 Aug 2026
- S55SEBI final order (28 Oct 2026) issues regulatory censure against Axis Capital · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 30 Oct 2026
- S56CFO Puneet Sharma resigns (relieved 31 Aug 2026); board approves re-appointment of Munish Sharda as ED · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 29 Jun 2026
- S57Board appoints Rajeev Mantri as Chief Financial Officer · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 18 Jul 2026
- S58RBI approval: re-appointment of Munish Sharda as Executive Director from 27 Feb 2027 · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 4 Nov 2026
- S59RBI approves amended GDR deposit agreement (voting rights for GDR holders, subject to conditions) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 30 Jan 2026
- S61EPFO demand of ₹1.14 crore (interest and damages, delayed pension-scheme remittance) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 4 Feb 2026
- S62RBI monetary penalty of ₹29.6 lakh (order 29 Apr 2025) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 3 May 2025
- S63RBI (Foreign Exchange Dept) compounding penalty of ₹37.3 lakh · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 13 Feb 2025
- S64PMLA Appellate Tribunal fine reduced to ₹39.2 lakh (order 27 Mar 2025) · NSE (company filing, nsearchives.nseindia.com) · Tier 1: company or exchange filing · 27 Jun 2025
Changes to this page (v1 · 11 Nov 2026)
- v1 · 11 Nov 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a SEBI-registered adviser and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a SEBI-registered investment adviser.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Content is not an offer or solicitation to buy or sell any security.
Read the full disclaimerHide the full disclaimer
Cityfort publishes educational content that explains how listed companies work. Cityfort is not registered with the Securities and Exchange Board of India (SEBI) as an Investment Adviser or Research Analyst and does not provide investment advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security.
All information is taken from publicly available sources, mainly company filings on BSE and NSE, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management are reported as statements, with their date and source; they are not our forecasts.