Financial Services · NSE: TATACAP · BSE: 544574
Tata Capital: how the business works
Tata Capital lends to 9.2 million customers in India, from home and personal loans to business and vehicle loans, and earned ₹4,846 crore of profit in FY26.
Follow Tata Capital
Email me when Tata Capital's page is updated after results.
We store your email address with Kit, our email provider, which also records when you sign up and whether you open or click our emails. We send a confirmation email first. See our privacy policy.
Tata Capital Limited · Mumbai, Maharashtra · Founded 1991
Updated for Q2 FY27 · checked
- Total income, FY26
- ₹31,583 cr
- Profit for shareholders, FY26
- ₹4,846 cr
- Loans managed (net AUM), 30 Sep 2026
- ₹308,030 cr
- Customers, 30 Sep 2026
- 9.2 million
- Promoter group holding, Sep 2026
- 85.41%
The short version
Tata Capital in 5 points
1 · What it sells
Tata Capital lends to people and businesses, from home loans and loans against property to personal, small-business, corporate and vehicle loans, and its loans under management were ₹308,030 crore at 30 Sep 2026.
2 · Who pays it
Borrowers pay Tata Capital interest, and at 30 Sep 2026 individuals (including vehicle loans) took 56.7% of its loans under management, small and mid-sized businesses 28.7% and larger companies 14.6%.
3 · What it keeps from ₹100
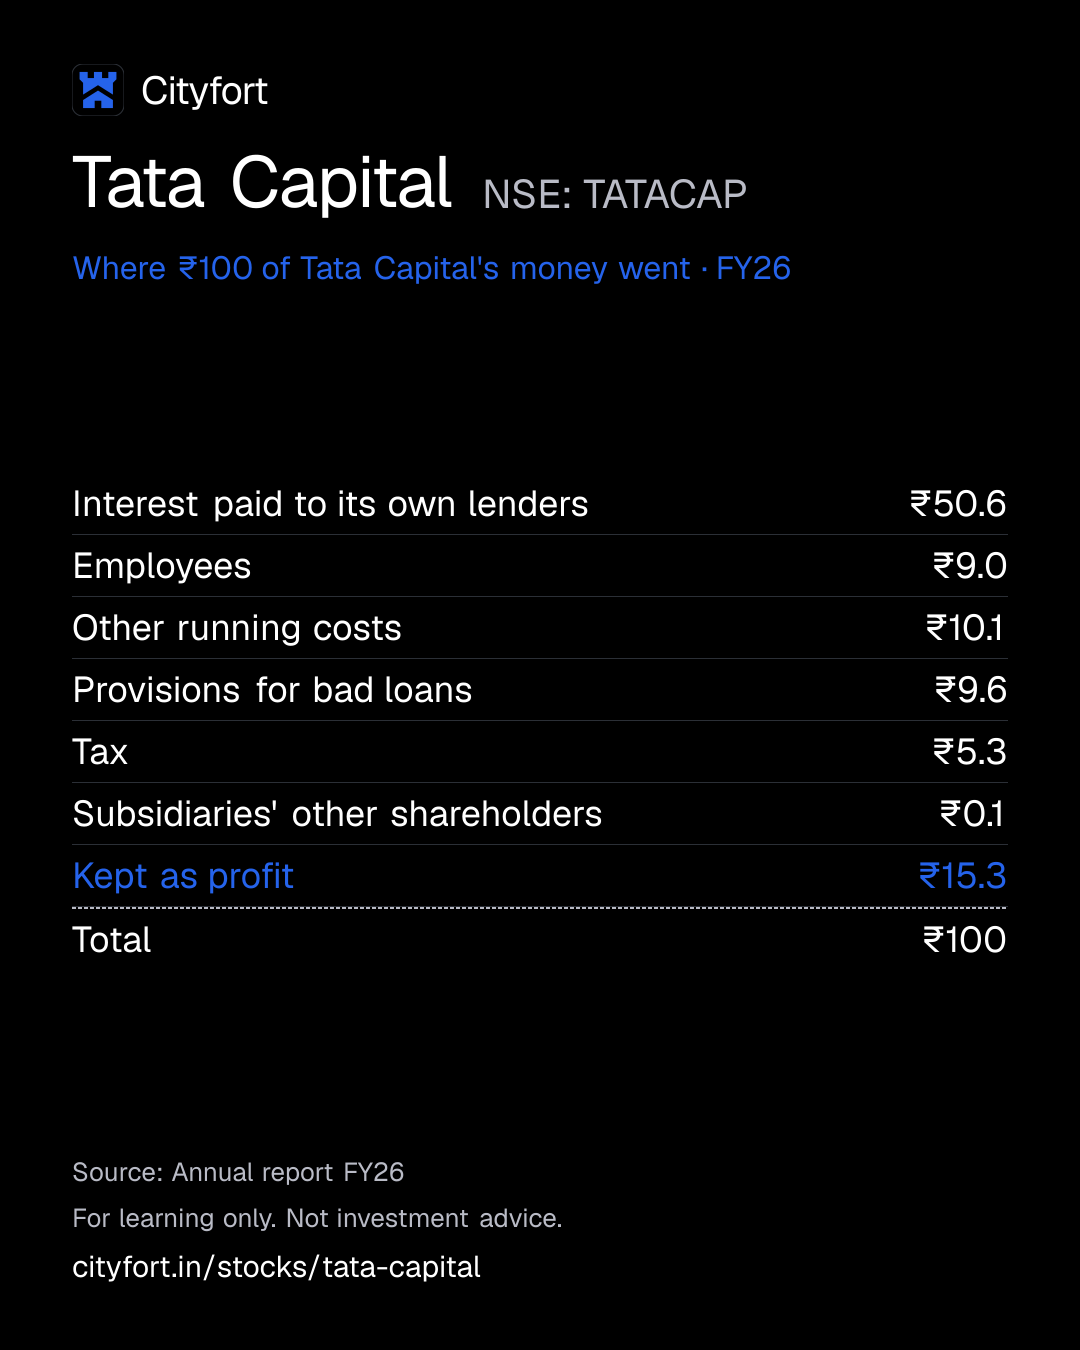
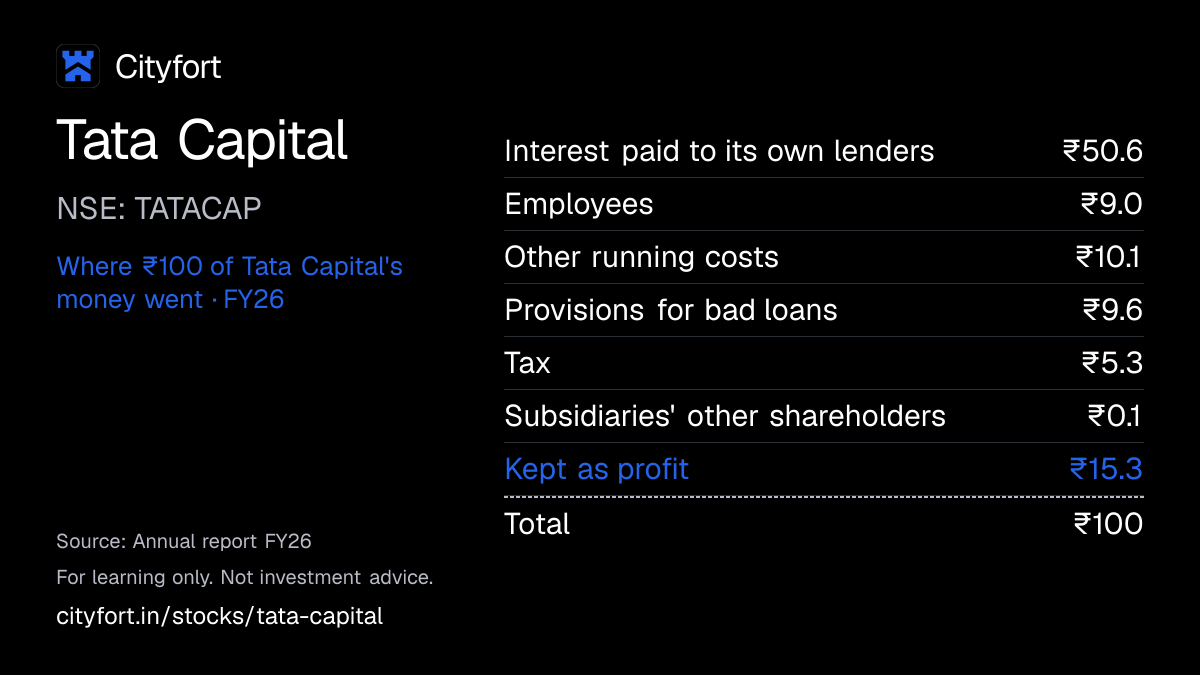
Of every ₹100 that came in during FY26, Tata Capital kept ₹15.3 as profit after ₹50.6 of interest to its lenders and ₹9.6 of bad-loan provisions, or ₹15.4 without a one-time ₹44 crore labour-code charge.
4 · Where the operating profit comes from
Tata Capital's profit comes mainly from the gap between the interest it earns and the interest it pays, which was ₹12,667 crore of net interest income in FY26, against ₹2,930 crore of fees and other income.
5 · The one thing to watch
Tata Capital's Motor Finance book, the former Tata Motors Finance, had 8.7% of its loans in stage 3 at 30 Sep 2026, against 1.3% for the rest, and shrank from ₹30,374 crore in Jun 2025 to ₹23,591 crore.
Sources: From Tata Capital's FY26 annual report and its Q2 FY27 investor presentation · checked
01Where the money goes · FY26
Where does ₹100 of Tata Capital's money go?
Tata Capital · FY26
Receipt for every ₹100
| Interest paid to its own lenders | ₹50.6 |
|---|---|
| Employees | ₹9.0 |
| Other running costs | ₹10.1 |
| Provisions for bad loans | ₹9.6 |
| Tax | ₹5.3 |
| Subsidiaries' other shareholders | ₹0.1 |
| Kept as profit | ₹15.3 |
| Total | ₹100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly ₹100 because of rounding.
How this is worked out
Of every ₹100 that came in to the Tata Capital group in FY26 (interest ₹28,652 crore + fees and other income ₹2,930 crore), Cityfort calculation from the FY26 annual report. A ₹5 crore share of associates' profit is left out. Without the one-time labour-code charge (₹33 crore after tax, as the company states it), ₹15.4 would have been kept.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report results, explained in 5 points.
We'll email you once a week with what changed on Cityfort. Facts only, no tips. Unsubscribe any time.
We store your email address with Kit, our email provider, which also records when you sign up and whether you open or click our emails. We send a confirmation email first. See our privacy policy.
02The business in one line
What does Tata Capital do?
Borrowers pay Tata Capital interest on their loans; about half of that money goes on interest to its own lenders, then staff, running costs and provisions for bad loans, and what's left is profit.
- In FY26 borrowers paid the Tata Capital group ₹28,652 crore of interest. Fees and other income added ₹2,930 crore.
- Interest paid to banks and bondholders took ₹15,985 crore. ₹4,846 crore was left as profit for shareholders.
03Who pays it
Who pays Tata Capital?
Tata Capital does not disclose how much each type of customer pays.
Home buyers
Pay interest on home loans: 15.6% of loans under management at 30 Sep 2026.
Property owners
Pay interest on loans against property: 14.2% of loans under management.
Individuals and small traders
Personal and business loans 9.1%, two-wheeler and 'CEQ' loans 4.8%, other retail loans 5.3% of loans under management.
Small and mid-sized businesses (SME)
Pay interest on business loans: 28.7% of loans under management, up from 25.3% in Jun 2025.
Larger companies
Pay interest on corporate loans: 14.6% of loans under management.
Vehicle owners and fleet operators
Pay interest on Motor Finance loans, mostly commercial vehicles: 7.7% of loans under management, down from 12.8% in Jun 2025.
How spread out the customers are
Tata Capital does not disclose income by customer. It had 9.2 million customers at 30 Sep 2026. The shares above are of loans under management (₹308,030 crore), not of income.
04How it makes money
How does Tata Capital make money?
A lender earns the gap between the interest it charges and the interest it pays
Tata Capital borrows from banks and bond markets on AAA ratings tied to the Tata group. It lends at higher rates across 25+ loan types. Running costs per ₹100 of net income were ₹37.9 in FY23, ₹42.1 in FY25 and ₹38.3 in FY26.
Running costs per ₹100 of net income (cost-to-income, Cityfort calculation from the FY26 annual report)
₹42.1₹38.3
FY25 to FY26
- Tata group backing supports AAA credit ratings
- AAA ratings let it borrow from banks and bond markets
- It lends to individuals, small firms and companies at higher rates
- The gap between interest earned and paid covers staff and bad loans
- Branches and 9.2 million customers bring repeat and new loans
- Profit adds to capital, which supports more lending
↺ Step 6 feeds back into step 1.
05Business segments · FY26
Which businesses make up Tata Capital?
Financing activity
96.6%All the lending: retail, SME, corporate and vehicle loans. Result is profit before tax, after interest and provisions.
Revenue ₹30,785 cr · Operating profit ₹6,402 cr
Investment activity
1.4%Its own investments, including private equity funds it sponsors and manages.
Revenue ₹439 cr · Operating profit ₹87.8 cr
Others
2%Advisory, wealth management, selling financial products and equipment leasing. Revenue counts sales between segments.
Revenue ₹634 cr · Operating profit ₹112 cr
How the mix changed
- Financing activity
- Investment activity
- Others
Revenue by segment, FY25 to FY26.
₹ crore
See the numbers
06The numbers · Consolidated · ₹ crore
How has Tata Capital done?
Net interest income
₹12,667 crFY26
Net interest income (interest earned minus interest paid) rose every year, from ₹4,201 crore in FY22 to ₹12,667 crore in FY26; FY25's ₹10,694 crore is the first year with Tata Motors Finance.
* FY22: Before TMF merger; was a CIC; FY23: Before TMF merger; was a CIC; FY24: Before Tata Motors Finance merger; FY25: First year with Tata Motors Finance; Q3 FY25: Recast to include TMF.
₹ crore · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net profit
₹4,846 crFY26
Profit for shareholders rose every year, from ₹1,648 crore in FY22 to ₹4,846 crore in FY26; FY23 includes an ₹815 crore pre-tax gain on ceasing to count some companies as associates.
* FY22: Before TMF merger; was a CIC; FY23: Before TMF merger; was a CIC; FY24: Before Tata Motors Finance merger; FY25: First year with Tata Motors Finance.
₹ crore
See the yearly numbers
See the quarterly numbers
Net interest margin
5.2%FY26
Net interest margin (NII as a share of average loans), as the company reports it for full years, was 5.1% in FY23, 5.0% in FY24 and 5.2% in FY25 and FY26.
% · as reported by the company
See the numbers
Bad loans (gross NPA)
2.00%FY26
Gross stage 3 loans (overdue more than 90 days, similar to NPAs) were 1.5% in FY24, 2.2% at Sep 2025 after the merger and 1.9% at Sep 2026.
* FY22: Before TMF merger; was a CIC; FY23: Before TMF merger; was a CIC; FY24: Before Tata Motors Finance merger; FY25: First year with Tata Motors Finance.
% of loans · gross and net (after provisions) non-performing assets
See the yearly numbers
See the quarterly numbers
See all yearly numbers
† Restated by the company. EPS is basic, as filed. Q1 FY26 (₹2.5) is from the prospectus, which gives one decimal. FY26 EPS uses the year's weighted share count, which was below the 4,244,869,037 shares after the Oct 2025 IPO.
Net interest income = interest earned on loans and investments minus interest paid on deposits and borrowings. Provisions = money set aside for loans that may not be repaid. Financial year runs April to March.
- Figures are for the Tata Capital group, including Tata Capital Housing Finance. Stage 3, provision cover, NIM, ROA and ROE are group figures as the company reports them. Capital adequacy (CRAR) is for Tata Capital alone.
- Tata Motors Finance is counted from 1 Apr 2024 (the merger took effect on 8 May 2025). FY25 and FY26 include it; FY22–FY24 do not, and the prospectus says these years are not entirely comparable. All eight quarters include it; Q3 FY25 was recast in the Q3 FY26 filing.
- Until 1 Jan 2024 Tata Capital was a core investment company (CIC), holding the lending companies, so no lender CRAR applies to FY22 and FY23. The CIC capital ratio it reported instead (adjusted net worth ÷ risk-weighted assets, 30% minimum) was 61% and 64%.
- Gross and net NPA are shown as stage 3 loans, the measure Tata Capital reports. It has not published a combined figure including Tata Motors Finance for Dec 2024, so Q3 FY25 is blank.
- Net interest margin is reported only for full years, and not for FY22. ROA is profit ÷ average net loans, as the company defines it, not ÷ total assets.
- Cost-to-income is a Cityfort calculation from the annual accounts: operating expenses ÷ (net interest income + other income). The company's own FY26 figure is 38.6%, because it counts the ₹44 crore labour-code charge.
- Tata Capital funds itself by borrowing, so deposits and CASA are not applicable. NBFC filings report no CET1; management said on the 27 Oct 2026 call that CET1 for Tata Capital alone was 14.7%.
- Loans are net loans on the balance sheet. Loans under management (net AUM), which also count loans sold to others, were ₹277,275 crore at 31 Mar 2026 and ₹308,030 crore at 30 Sep 2026.
- Net profit is profit for Tata Capital's shareholders. In Q2 FY27 total profit was ₹1,831.88 crore, of which ₹172.01 crore belonged to subsidiaries' other shareholders, up from ₹21.65 crore in Q2 FY26; the filing does not say why.
- One-time items: FY23 includes an ₹814.58 crore pre-tax gain on ceasing to count some companies as associates. Q3 FY26 has a ₹44.04 crore labour-code charge. Q2 FY27 income includes a ₹186.32 crore gain of the same associate type.
Sources (10)
- Annual Report FY23 (32nd, 2022-23)
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
- Investor presentation Q4 FY26
- Unaudited standalone and consolidated financial results, quarter ended 30 Jun 2026 (Q1 FY27)
- Unaudited standalone and consolidated financial results, quarter and nine months ended 31 Dec 2025 (Q3 FY26)
- Audited standalone and consolidated financial results, quarter and year ended 31 Mar 2026 (Q4 FY26)
- Investor presentation Q2 FY26
- Unaudited standalone and consolidated financial results, quarter and half year ended 30 Sep 2026 (Q2 FY27)
- Investor presentation Q2 FY27
07Who runs it
Who runs Tata Capital, and did they deliver?
Saurabh Agrawal
Chairman (non-executive)
ICRA says he is from Tata Sons, the parent.
Rajiv Sabharwal
Managing Director and CEO
Rakesh Bhatia
Chief Financial Officer
Sarita Kamath
Chief Legal and Compliance Officer and Company Secretary
What they said, and what happened
1 partly delivered · 1 missed · 3 too early to tell
Said on 19 Jan 2026
FY26 guidance (Q3 FY26 presentation) included loans under management growing 18–20%, credit cost of about 1.2%, ROA of 2.0–2.1%, ROE of 13–14% and net NPA below 1.0%, excluding non-recurring items.
Partly deliveredWhat happened
Management said on 23 Apr 2026 that loans under management grew 20%. The company reports FY26 credit cost of 1.2%, ROA of 2.0%, net stage 3 of 0.9% and ROE of 12.9%, below the 13–14% range.
Said on 23 Apr 2026
Management said on the Q4 FY26 call that it expected Motor Finance growth to resume from the first half of FY27.
MissedWhat happened
Motor Finance loans fell from ₹25,390 crore (Mar 2026) to ₹23,591 crore (Sep 2026). On 27 Oct 2026 Rajiv Sabharwal said growth was lagging "by two to three quarters".
Said on 23 Apr 2026
Management said on the Q4 FY26 call that it is targeting an ROA of 2% for the Motor Finance business by FY28.
Too early to tellWhat happened
Management said on the same call that Motor Finance broke even in Q3 FY26.
Said on 27 Oct 2026
FY28 guidance: loans under management growing 23–25% a year from FY25, ROA of 2.5–2.7% and ROE of 17–18% (repeated in the Q2 FY27 presentation).
Too early to tellWhat happened
In Q2 FY27 the company reports annualised ROA of 2.3% and ROE of 14.0%, excluding non-recurring items.
Said on 28 Jul 2026
Management said on the Q1 FY27 call that it was "fairly confident of keeping the credit costs within the guidance" of about 1%.
Too early to tellWhat happened
Credit cost was 1.0% in Q1 FY27 and 0.9% in Q2 FY27 (annualised, as the company reports it).
Sources (9)
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
- Earnings conference call transcript Q2 FY27 (27 Oct 2026)
- Investor presentation Q3 FY26
- Earnings conference call transcript Q4 FY26 (23 Apr 2026)
- Investor presentation Q4 FY26
- Investor presentation Q2 FY27
- Earnings conference call transcript Q1 FY27 (28 Jul 2026)
- Investor presentation Q1 FY27
08What could go wrong
What could go wrong for Tata Capital?
- Execution
Bad loans in the Motor Finance book
Motor Finance had 8.7% of loans in stage 3 at 30 Sep 2026, with 37.7% provision cover. Its book fell from ₹30,374 crore (Jun 2025) to ₹23,591 crore. Rajiv Sabharwal said on 27 Oct 2026 that growth lags plan "by two to three quarters".
Watch Motor Finance loans and its stage 3 share each quarter.
- Other
Lower provision cover after the merger
Provisions covered 77.1% of stage 3 loans in FY23 and 52.8% at Sep 2025, before rising to 58.6% at Sep 2026. Provision cover is listed second among the prospectus's top ten risk factors.
Watch Provision cover and gross stage 3 (1.9% at 30 Sep 2026).
- Pricing
Interest rates
At 30 Sep 2026, 66% of loans and 48% of liabilities were floating-rate. Management said on 27 Oct 2026 that NIM fell about 10 basis points in Q2 FY27 and cost of funds rose to 7.33%.
Watch Full-year NIM (5.2% in FY26) and cost of funds.
- Debt
Capital and future share issues
Capital adequacy for Tata Capital alone fell from 18.96% (Mar 2026) to 17.28% (Sep 2026); RBI's minimum is 15%. Rajiv Sabharwal said on 27 Oct 2026 that, on current growth plans, it expects to raise capital towards the second half of FY28.
Watch Capital adequacy and Tier I each quarter, and any fund-raise announcement.
- Cash and liquidity
Funding depends on borrowing and its ratings
Borrowings were ₹260,846 crore at 30 Sep 2026. The prospectus says a rating downgrade could raise its cost of borrowing, which was 7.8% in FY25.
Watch ICRA and CARE ratings (AAA, Stable) and cost of funds.
- Concentration
Property and unsecured loans
Home loans, loans against property and developer finance were 34.7% of gross loans at 30 Jun 2025. Unsecured loans were 20.0%, per the prospectus.
Watch The loan mix in each quarterly presentation.
- Regulation
Possible action over bond-holder limits
The prospectus says holder numbers of some Tata Motors Finance NCDs and Tata Capital CRPS went past legal limits. It says the company may face regulatory action, including penal action.
Watch Any regulator order or penalty disclosed to the exchanges.
Sources (7)
- Investor presentation Q2 FY27
- Earnings conference call transcript Q2 FY27 (27 Oct 2026)
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
- Unaudited standalone and consolidated financial results, quarter ended 30 Jun 2026 (Q1 FY27)
- Unaudited standalone and consolidated financial results, quarter and half year ended 30 Sep 2026 (Q2 FY27)
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
- CARE Ratings press release: Tata Capital Limited (revised), ratings reaffirmed
09Supporters and critics
What do supporters and critics point to?
What supporters point to
- ICRA (21 Jul 2026) and CARE (8 Apr 2026) rate its debt AAA (Stable); ICRA calls it the Tata group's sole financial services business.
- Profit for shareholders rose every year, from ₹1,648 crore in FY22 to ₹4,846 crore in FY26.
- Cost-to-income, as the company reports it, fell from 39.7% in Q2 FY26 to 35.3% in Q2 FY27.
- Gross stage 3 loans fell from 2.2% at Sep 2025 to 1.9% at Sep 2026.
- Management said on 23 Apr 2026 that Motor Finance broke even in Q3 FY26.
What critics point to
- ROE was 12.8% in FY26 and 14.0% in Q2 FY27; management's FY28 guidance (27 Oct 2026) is 17–18%.
- Provision cover fell from 77.1% in FY23 to 58.6% at Sep 2026.
- The Motor Finance book shrank every quarter from Jun 2025, and 8.7% of it was in stage 3 at Sep 2026.
- Q2 FY27 income included a ₹186 crore gain from ceasing to count some companies as associates; the presentation shows no non-recurring item for the quarter.
- The prospectus says holder limits on some bonds and preference shares were exceeded, which may bring regulatory action.
10What to watch next
What should you watch next at Tata Capital?
Next event
Q3 FY27 results (date not announced)
Date not announced yet.
Motor Finance
Loans were ₹23,591 crore at 30 Sep 2026 and 8.7% were in stage 3. Management said on 23 Apr 2026 it expected growth to resume from the first half of FY27.
Capital
Capital adequacy was 17.28% at 30 Sep 2026 against RBI's 15% minimum. Rajiv Sabharwal said on 27 Oct 2026 the company expects to raise capital sometime towards the second half of FY28.
Interest margin
Management said on 27 Oct 2026 that its asset-liability committee approved lending-rate increases of 25 basis points for Tata Capital and 20 for its housing subsidiary, from 1 Nov 2026. It said it expects margin plus fees to hold in Q3 and improve from Q4.
11Key facts
Key facts about Tata Capital
- What does Tata Capital do?
- Tata Capital is a Mumbai-based non-bank lender (NBFC) controlled by Tata Sons. It gives home, personal, small-business, corporate and vehicle loans in India. Its loans under management (net AUM) were ₹308,030 crore at 30 Sep 2026.
- How does Tata Capital make money?
- Tata Capital earns mostly interest on loans. In FY26 interest was ₹28,652 crore of the group's ₹31,583 crore total income; fees, leasing rent and other income made up the other ₹2,930 crore.
- Who are Tata Capital's customers?
- Tata Capital had 9.2 million customers at 30 Sep 2026. Individuals (retail, including vehicle loans) took 56.7% of its loans under management, small and mid-sized businesses (SME) 28.7% and larger companies 14.6%.
- How big is Tata Capital?
- Tata Capital's group total income was ₹31,583 crore in FY26. Profit for its shareholders was ₹4,846 crore in FY26, up from ₹3,665 crore in FY25; both years include Tata Motors Finance.
- Who owns Tata Capital?
- Tata Sons owned 78.80% of Tata Capital at 30 Sep 2026, and the Tata promoter group as a whole 85.41%. Foreign institutions held 5.06%, Indian institutions 3.88% and other investors 5.01%, per the shareholding pattern.
- When did Tata Capital list on the stock exchanges?
- Tata Capital's shares listed on NSE and BSE on 13 Oct 2025. Its IPO of 6–8 Oct 2025 sold 475,824,280 shares at the issue price of ₹326 each, ₹15,511.87 crore in all.
- What happened to Tata Motors Finance?
- Tata Motors Finance merged into Tata Capital with effect from 8 May 2025, with accounts combined from 1 Apr 2024. Tata Capital's Motor Finance book was ₹23,591 crore, 7.7% of its loans under management, at 30 Sep 2026.
- Where does Tata Capital get the money it lends?
- Tata Capital borrows it. Group borrowings were ₹260,846 crore at 30 Sep 2026. Bank loans were 39% of borrowings, bonds (NCDs) 35%, foreign loans and notes 12%, commercial paper and short-term loans 9% and National Housing Bank 3%.
- How many of Tata Capital's loans are not being repaid?
- Tata Capital's gross stage 3 loans (overdue more than 90 days, similar to NPAs) were 1.9% of loans at 30 Sep 2026, and 0.8% after provisions, on a group basis.
Sources (5)
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
- Investor presentation Q2 FY27
- Shareholding pattern as on 30 Sep 2026 (Reg 31(1)(b))
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
- Earnings conference call transcript Q2 FY27 (27 Oct 2026)
Terms on this page
- Credit rating
- FII and DII holding
- Gross and net NPA
- Market capitalisation
- Net interest margin (NIM)
- Net profit
- Promoter holding
- Provision coverage ratio (PCR)
- Public shareholding
- Return on equity (ROE)
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does Tata Capital sell?
Home loans
Mostly through subsidiary Tata Capital Housing Finance. Home loans were ₹48,163 crore, 15.6% of loans under management, at 30 Sep 2026.
Loans against property
Loans secured on a home or shop the borrower already owns: ₹43,617 crore at 30 Sep 2026.
Personal and business loans
Loans paid straight to individuals and small traders: ₹28,076 crore at 30 Sep 2026.
Two-wheeler, 'CEQ' and other retail loans
Two-wheeler and what the presentation labels 'CEQ' loans were ₹14,758 crore. Education, microfinance, share-backed and car loans were ₹16,464 crore (30 Sep 2026).
Small and mid-sized business (SME) loans
Loans to smaller firms: ₹88,500 crore, 28.7% of loans under management, at 30 Sep 2026.
Corporate loans
Loans to larger companies: ₹44,862 crore, 14.6% of loans under management, at 30 Sep 2026.
Motor Finance
The former Tata Motors Finance: commercial vehicle and some car loans. ₹23,591 crore at 30 Sep 2026, down from ₹30,374 crore in Jun 2025.
What it does
- Does: Lends from 1,515 branches in 26 states and union territories (30 Sep 2026)
- Does: Earned ₹1,696 crore of fees and commission in FY26; its Others segment covers advice, wealth management and selling financial products
- Does: Runs an operating-lease business; rental income was ₹445 crore in FY26
What it does not do
- Does not: It is not a bank; RBI registers it as a non-bank lender (NBFC) and places it in the 'upper layer'
- Does not: It is not Tata Motors: it took over Tata Motors Finance, the vehicle-loan company of the Tata Motors group, in 2025
- Does not: It is not Tata Sons, which is its parent and owned 78.80% at 30 Sep 2026
Sources (1)
13How the money flows
13How the money flows · FY26
How does money flow through Tata Capital?
Money in
- Interest on loans and investments₹28,652 cr
- Fees, leasing rent and other income₹2,930 cr
The company
Tata Capital
₹31,583 cr came in
Money out
- Interest paid to banks, bondholders and other lenders₹15,985 cr
- Employees₹2,828 cr
- Other running costs and depreciation (incl. one-time ₹44 cr labour-code charge)₹3,189 cr
- Provisions for bad loans₹3,023 cr
- Tax₹1,671 cr
- Profit of subsidiaries' other shareholders₹44.8 cr
- Profit for Tata Capital's shareholders₹4,846 cr
- These are the Tata Capital group's FY26 accounts, including home-loan subsidiary Tata Capital Housing Finance and the merged Tata Motors Finance.
- Borrowers paid ₹28,652 crore of interest. Fees, leasing rent and other income added ₹2,930 crore.
- Tata Capital paid ₹15,985 crore of interest to the banks and bondholders who lend to it.
- Staff cost ₹2,828 crore and other running costs ₹3,189 crore. ₹3,023 crore was set aside for loans that may not be repaid.
- After ₹1,671 crore of tax and ₹45 crore belonging to subsidiaries' other shareholders, ₹4,846 crore was profit.
14What it needs to run
14What it needs to run
What does Tata Capital need to run?
Borrowed money
Group borrowings were ₹260,846 crore at 30 Sep 2026. Management said its cost of funds was 7.33% in Q2 FY27, up from 7.28%.
Credit ratings
AAA (Stable) from ICRA (21 Jul 2026) and CARE (8 Apr 2026). CARE cites strong parentage; ICRA notes equity put in by Tata Sons.
Capital
Capital adequacy (own capital as a share of risk-weighted loans) was 17.28% for Tata Capital alone at 30 Sep 2026. RBI's minimum is 15%.
Branches
1,515 branches in 1,094 locations across 26 states and union territories at 30 Sep 2026, up from 539 branches in Mar 2023.
People
31,655 employees on its rolls at 30 Sep 2026, management said on the Q2 FY27 call.
RBI registration
RBI registers Tata Capital as an NBFC (investment and credit company) in the 'upper layer', whose members had to list their shares.
Sources (8)
- Investor presentation Q2 FY27
- Earnings conference call transcript Q2 FY27 (27 Oct 2026)
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
- CARE Ratings press release: Tata Capital Limited (revised), ratings reaffirmed
- Unaudited standalone and consolidated financial results, quarter and half year ended 30 Sep 2026 (Q2 FY27)
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
- Investor presentation Q4 FY26
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
15Competitors and what protects it
15Competitors and what protects it
Who does Tata Capital compete with?
Bajaj Finance
NSE: BAJFINANCE
Listed as a peer in Tata Capital's prospectus. Its FY25 revenue from operations was ₹69,684 crore, against Tata Capital's ₹28,313 crore.
Shriram Finance
NSE: SHRIRAMFIN
Listed as a peer in the prospectus, with FY25 revenue from operations of ₹41,834 crore.
Cholamandalam Investment and Finance
Listed as a peer in the prospectus, with FY25 revenue from operations of ₹25,846 crore.
HDB Financial Services
NSE: HDBFS
Listed as a peer in the prospectus, with FY25 revenue from operations of ₹16,300 crore.
L&T Finance
Listed as a peer in the prospectus, with FY25 revenue from operations of ₹15,924 crore.
What protects the business
Each strength is scored 1 (weak) to 5 (strong) for the business, with the reason. It is not a rating of the share.
- Cost of borrowing4 of 5
AAA (Stable) from ICRA and CARE. ICRA calls it the sole financial services business of the Tata group, which owned 85.4% at 31 Mar 2026.
- Range of loans3 of 5
25+ loan products split 56.7% retail, 28.7% SME and 14.6% corporate at 30 Sep 2026, per the company.
- Distribution3 of 5
1,515 branches in 26 states and union territories and 9.2 million customers at 30 Sep 2026.
- Running costs3 of 5
Cost-to-income, as the company reports it, fell from 39.7% in Q2 FY26 to 35.3% in Q2 FY27.
Weak spot
The Motor Finance book
The former Tata Motors Finance had 8.7% of its loans in stage 3 (bad loans) at 30 Sep 2026, against 1.3% for the rest of Tata Capital. Its book shrank every quarter from Jun 2025.
Sources (4)
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
- CARE Ratings press release: Tata Capital Limited (revised), ratings reaffirmed
- Investor presentation Q2 FY27
16Where growth could come from
16Where growth could come from
Where could Tata Capital's growth come from?
Tata Capital's Q2 FY27 presentation (27 Oct 2026) gives FY28 guidance. It is for loans under management to grow 23–25% a year from FY25 to FY28 and profit by over 30% a year. It guides ROA of 2.5–2.7%, ROE of 17–18%, cost-to-income of 33–34%, and credit cost and net NPA each below 1.0%. On the call that day, MD and CEO Rajiv Sabharwal said: "We don't want to revise anything."
Small-business (SME) loans
Working₹88,500 cr (Sep 2026), from ₹64,099 cr (Sep 2025)
SME loans rose from 26.3% to 28.7% of loans under management over the year to 30 Sep 2026.
Status: Working, on track against what the company said.
Corporate loans
Working₹44,862 cr (Sep 2026), from ₹28,441 cr (Sep 2025)
Corporate loans rose from 11.7% to 14.6% of loans under management over the same year.
Status: Working, on track against what the company said.
Retail loans other than Motor Finance
Working₹151,077 cr (Sep 2026), from ₹123,035 cr (Sep 2025)
Home loans and loans against property were the two largest retail lines, at ₹48,163 crore and ₹43,617 crore.
Status: Working, on track against what the company said.
Motor Finance
Behind₹23,591 cr (Sep 2026), from ₹28,322 cr (Sep 2025)
Management said in Apr 2026 it expected growth to resume from the first half of FY27. Non-Tata brands were 30% of its Q2 FY27 disbursements.
Status: Behind, behind the company's own plan.
Gold loans
NewAbout 88.6% of Yogakshemam Loans (board approval, 13 Jul 2026)
The board approved buying a gold-loan NBFC. ICRA says the value before new money is at most ₹318 crore, and the deal also includes about ₹93 crore of new money. It needs approvals.
Status: New, recently announced.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
Sources (5)
- Investor presentation Q2 FY27
- Earnings conference call transcript Q2 FY27 (27 Oct 2026)
- Earnings conference call transcript Q4 FY26 (23 Apr 2026)
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
17Financial strength: capital, bad loans, deposits
17Financial strength · FY26
How strong is Tata Capital's balance sheet?
- Loans given (advances)₹2.68 lakh cr
- Capital adequacy (CRAR)
- 18.96%
- capital as a share of risk-weighted loans; regulators set a minimum
- Gross NPA
- 2.0%
- loans not being repaid, as % of all loans
- Net NPA
- 0.9%
- the same, after money already set aside
- Provision cover
- 56.2%
- share of bad loans already provided for
- Cost to income
- 38.3%
- ₹ of running costs per ₹100 of income after interest paid
- Return on assets
- 2.0%
- profit as % of everything the lender owns
- Return on equity
- 12.8%
- profit as % of shareholders' money
Figures as on FY26 year end. Reported by the company; see the dates on each source.
18Who owns it
18Who owns it · Q2 FY27
Who owns Tata Capital?
- Promoters (founders or parent company)85.4%
- Foreign institutions (FII)5.1%
- Indian institutions (DII)3.9%
- Public and others5.6%
Promoter pledge
No promoter shares were pledged in Q2 FY27.
How ownership changed
* Pledged = share of the promoters' own holding reported as pledged. In older filings this can include shares “otherwise encumbered”; the governance flags say when.
† Others = Employee welfare trust (neither promoter nor public).
19What it does with profit
19What it does with profit
What does Tata Capital do with its profit?
Dividend per share
₹0.57FY26
Dividend paid for each share, by financial year.
₹ per share
See the numbers
Money raised · 13 May 2025
Issued 183,867,495 shares to TMF Holdings as part of the payment for Tata Motors Finance (37 Tata Capital shares for every 100 Tata Motors Finance shares). The accounts value these shares at ₹4,162.76 crore.
₹4,163 cr
Money raised · 18 Jul 2025
Rights issue of 51,074,292 shares to existing shareholders, for about ₹1,751.85 crore.
₹1,752 cr
Money raised · 8 Oct 2025
IPO: 210,000,000 new shares at ₹326 raised ₹6,846.0 crore for Tata Capital. Another 265,824,280 shares sold by Tata Sons and IFC raised ₹8,665.87 crore for them, not the company.
₹6,846 cr
20Governance signals
20Governance signals
What do Tata Capital's governance filings show?
- Auditor
- T. P. Ostwal & Associates LLP (joint statutory auditor for FY27 to FY29) and M. P. Chitale & Co. (continuing joint statutory auditor)
- Auditor changes
- 13 Jul 2026: MSKA & Associates LLP → T. P. Ostwal & Associates LLP (Rotation under RBI's auditor guidelines; M. P. Chitale & Co. continues as the other joint auditor. The FY26 audit opinion was unmodified.)
- Audit qualifications
- None reported
- Related-party dealings
- Tata Sons owned 78.80% and the Tata promoter group 85.41% at 30 Sep 2026. TMF Holdings, a Tata Motors group company, received 183,867,495 shares for Tata Motors Finance in May 2025. Group insurers Tata AIG and Tata AIA hold shares that are counted as public.
- Credit rating
- ICRA AAA (outlook Stable), 21 Jul 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory · 8 Oct 2025
Possible regulatory action over bond-holder limits
The prospectus says some Tata Motors Finance bonds (NCDs) and Tata Capital preference shares (CRPS) were sold on by their first buyers. Holder numbers then went past legal limits, and it says the company "may be subject to regulatory action, including penal action".
other · 8 Oct 2025
Court cases listed in the prospectus
At 8 Oct 2025 the prospectus listed 284 criminal, 103 tax and 6 regulatory proceedings against the company, ₹757.51 crore where quantifiable. The criminal count includes cases in which the MD and CEO and two chief operating officers were impleaded along with the company. The company had filed 152,229 criminal cases itself.
auditor · 13 Jul 2026
Joint auditor rotated under RBI's rules
On 13 Jul 2026 the board appointed T. P. Ostwal & Associates LLP as joint auditor for FY27–FY29 in place of MSKA & Associates LLP, citing RBI's rotation guidelines.
Sources (5)
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
- Unaudited standalone and consolidated financial results, quarter and half year ended 30 Sep 2026 (Q2 FY27)
- Shareholding pattern as on 30 Sep 2026 (Reg 31(1)(b))
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
21What the market paid
21What the market paid · price as of 11 Nov 2026
What did the market pay for Tata Capital on 11 Nov 2026?
Price as of 11 Nov 2026 (shown for education; prices change daily).
Price as of 11 Nov 2026: ₹356.15, the NSE closing price. Market value: ₹151,181 crore, a Cityfort calculation from the 11 Nov 2026 NSE closing price and 4,244,869,037 shares in the Sep 2026 shareholding pattern. P/E divides market value by one year's profit. Here that is the four quarters to 30 Sep 2026 (₹5,966 crore), giving 25.3 (Cityfort calculation from the Q4 FY26 and Q2 FY27 results). Reported FY26 EPS is not used, because shares were issued during the year. P/B divides the price by book value per share. Book value was ₹47,778 crore of equity at 30 Sep 2026 (Q2 FY27 presentation, excluding perpetual bonds), or ₹112.55 a share, giving 3.16 (Cityfort calculation). EV/EBITDA is not shown, because interest is a lender's main cost.
- Share price
- ₹356.15
- Market value (market cap)
- ₹151,181 cr
- P/E
- 25.3×
- P/B
- 3.2×
Source: NSE security-wise bhavcopy, 11 Nov 2026 (TATACAP EQ close); Shareholding pattern as on 30 Sep 2026 (Reg 31(1)(b)); Audited standalone and consolidated financial results, quarter and year ended 31 Mar 2026 (Q4 FY26) and 2 more
Sources (5)
- NSE security-wise bhavcopy, 11 Nov 2026 (TATACAP EQ close)
- Shareholding pattern as on 30 Sep 2026 (Reg 31(1)(b))
- Audited standalone and consolidated financial results, quarter and year ended 31 Mar 2026 (Q4 FY26)
- Unaudited standalone and consolidated financial results, quarter and half year ended 30 Sep 2026 (Q2 FY27)
- Investor presentation Q2 FY27
22How it got here
22How it got here
How did Tata Capital get here?
1991
Milestone
Incorporated as Primal Investments & Finance
Incorporated on 8 Mar 1991 in Bombay; renamed Tata Capital Limited on 8 May 2007.
2024
Business-model change
Lending arms merged into the parent
Tata Capital Financial Services and Tata Cleantech Capital merged into Tata Capital from 1 Jan 2024. Until then it was a core investment company holding them.
2025
Business-model change
Tata Motors Finance merged in
The merger took effect on 8 May 2025, with accounts combined from 1 Apr 2024. It added ₹29,562 crore of loans at that date.
2025
Milestone
Rights issue
51,074,292 new shares for about ₹1,751.85 crore in Jul 2025.
2025
Milestone
Shares listed
RBI required upper-layer NBFCs to list. The ₹15,511.87 crore IPO at ₹326 a share led to listing on 13 Oct 2025.
2026
Milestone
Gold-loan acquisition approved
On 13 Jul 2026 the board approved buying about 88.6% of Yogakshemam Loans, a gold-loan NBFC, subject to approvals.
Sources (3)
- Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26
- Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements
- ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised)
23Sources and changes
Where every number on this page comes from
Sources (23 documents)
- S1Annual Report FY26 (35th, 2025-26), incl. standalone and consolidated financial statements · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 30 Jun 2026
- S2Annual Report FY25 (34th, 2024-25) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 2 Jun 2025
- S3Annual Report FY24 (33rd, 2023-24) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 11 Jun 2024
- S4Annual Report FY23 (32nd, 2022-23) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 22 May 2023
- S5Prospectus for the initial public offer (8 Oct 2025), incl. Restated Consolidated Financial Information FY23-FY25 and Q1 FY26 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 8 Oct 2025
- S6Unaudited standalone and consolidated financial results, quarter and half year ended 30 Sep 2026 (Q2 FY27) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 27 Oct 2026
- S7Investor presentation Q2 FY27 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 27 Oct 2026
- S8Earnings conference call transcript Q2 FY27 (27 Oct 2026) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 27 Oct 2026
- S10Unaudited standalone and consolidated financial results, quarter ended 30 Jun 2026 (Q1 FY27) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 28 Jul 2026
- S11Investor presentation Q1 FY27 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 28 Jul 2026
- S12Earnings conference call transcript Q1 FY27 (28 Jul 2026) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 28 Jul 2026
- S13Audited standalone and consolidated financial results, quarter and year ended 31 Mar 2026 (Q4 FY26) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 23 Apr 2026
- S14Investor presentation Q4 FY26 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 23 Apr 2026
- S15Earnings conference call transcript Q4 FY26 (23 Apr 2026) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 23 Apr 2026
- S16Unaudited standalone and consolidated financial results, quarter and nine months ended 31 Dec 2025 (Q3 FY26) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 19 Jan 2026
- S17Investor presentation Q3 FY26 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 19 Jan 2026
- S19Investor presentation Q2 FY26 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 28 Oct 2025
- S20Shareholding pattern as on 30 Sep 2026 (Reg 31(1)(b)) · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 30 Sep 2026
- S21Shareholding pattern as on 31 Mar 2026 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 31 Mar 2026
- S22Shareholding pattern as on 31 Dec 2025 · Tata Capital Ltd (company IR page) · Tier 1: company or exchange filing · 31 Dec 2025
- S24ICRA rating rationale: Tata Capital Limited, [ICRA]AAA (Stable) assigned to NCD, earlier ratings reaffirmed (revised) · ICRA Limited · Tier 2: rating agency or regulator · 21 Jul 2026
- S25CARE Ratings press release: Tata Capital Limited (revised), ratings reaffirmed · CARE Ratings Limited · Tier 2: rating agency or regulator · 8 Apr 2026
- S27NSE security-wise bhavcopy, 11 Nov 2026 (TATACAP EQ close) · National Stock Exchange of India · Tier 1: company or exchange filing · 11 Nov 2026
Changes to this page (v1 · 12 Nov 2026)
- v1 · 12 Nov 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a SEBI-registered adviser and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a SEBI-registered investment adviser.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Content is not an offer or solicitation to buy or sell any security.
Read the full disclaimerHide the full disclaimer
Cityfort publishes educational content that explains how listed companies work. Cityfort is not registered with the Securities and Exchange Board of India (SEBI) as an Investment Adviser or Research Analyst and does not provide investment advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security.
All information is taken from publicly available sources, mainly company filings on BSE and NSE, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management are reported as statements, with their date and source; they are not our forecasts.